

Treating international tax compliance as an annual filing chore is the fastest route to crippling IRS penalties. If you direct cross-border business operations or hold foreign financial interests, you already know how unsettling it is to face overlapping tax jurisdictions, opaque bilateral treaties, and aggressive withholding mandates. Establishing sound Global Tax Solutions for Businesses & Individuals isn’t about scrambling to file forms each spring. Unlike traditional, reactive accounting, it requires a deliberate multi-jurisdictional architecture that protects your hard-earned capital well before audits or reporting triggers occur.
You shouldn’t have to surrender peace of mind to bureaucratic complexity or risk double taxation on your global revenue. In this guide, you’ll discover how to master cross-border tax compliance, eliminate treaty pitfalls, and secure your international assets through an authoritative strategic advisory framework. We examine key foreign account reporting requirements, clarify FIRPTA withholding rules during real estate transactions, and reveal how dedicated CPA stewardship safeguards your worldwide enterprise for the long haul.
Key Takeaways
- Explore how comprehensive Global Tax Solutions for Businesses & Individuals eliminate double taxation by harmonizing foreign tax credits with bilateral treaty provisions.
- Uncover the stringent informational reporting and FIRPTA withholding mandates required to shield your foreign assets from severe statutory IRS penalties.
- Understand the vital distinction between reactive seasonal filing and proactive cross-border architecture designed before capital is deployed.
- Learn a structured four-phase strategic roadmap to systematically identify multi-jurisdictional nexus, audit exposure, and worldwide asset reporting requirements.
- See how year-round strategic stewardship from a dedicated CPA firm safeguards your international investments across Greensboro and beyond.
Navigating Global Tax Complexity for Cross-Border Businesses and Individuals
Operating across international boundaries introduces regulatory layers that conventional domestic accounting simply can’t resolve. For growing enterprises and private investors, foundational international taxation principles dictate how multiple sovereign authorities assert jurisdiction over the exact same revenue streams. Unlike standard tax preparation that merely records historical figures after taxable events occur, implementing effective Global Tax Solutions for Businesses & Individuals requires proactive structural foresight. This comprehensive approach harmonizes cross-border transactions, secures applicable bilateral treaty protections, and shields your enterprise from compounding statutory penalties.
To better understand how cross-border regulations influence corporate structures and reporting obligations, watch this helpful breakdown:
The Shifting Landscape of Cross-Border Taxation in 2026
Modern cross-border enforcement is driven by automated data exchange protocols between sovereign taxing authorities. The IRS exercises rigorous oversight by taxing U.S. citizens and resident aliens on their worldwide income, irrespective of where those funds are earned or deposited. Simultaneously, financial institutions track international wire movements and foreign asset values with unprecedented precision, meaning that missing even an informational filing threshold can trigger aggressive audit scrutiny.
Inbound vs. Outbound Financial Structures Explained
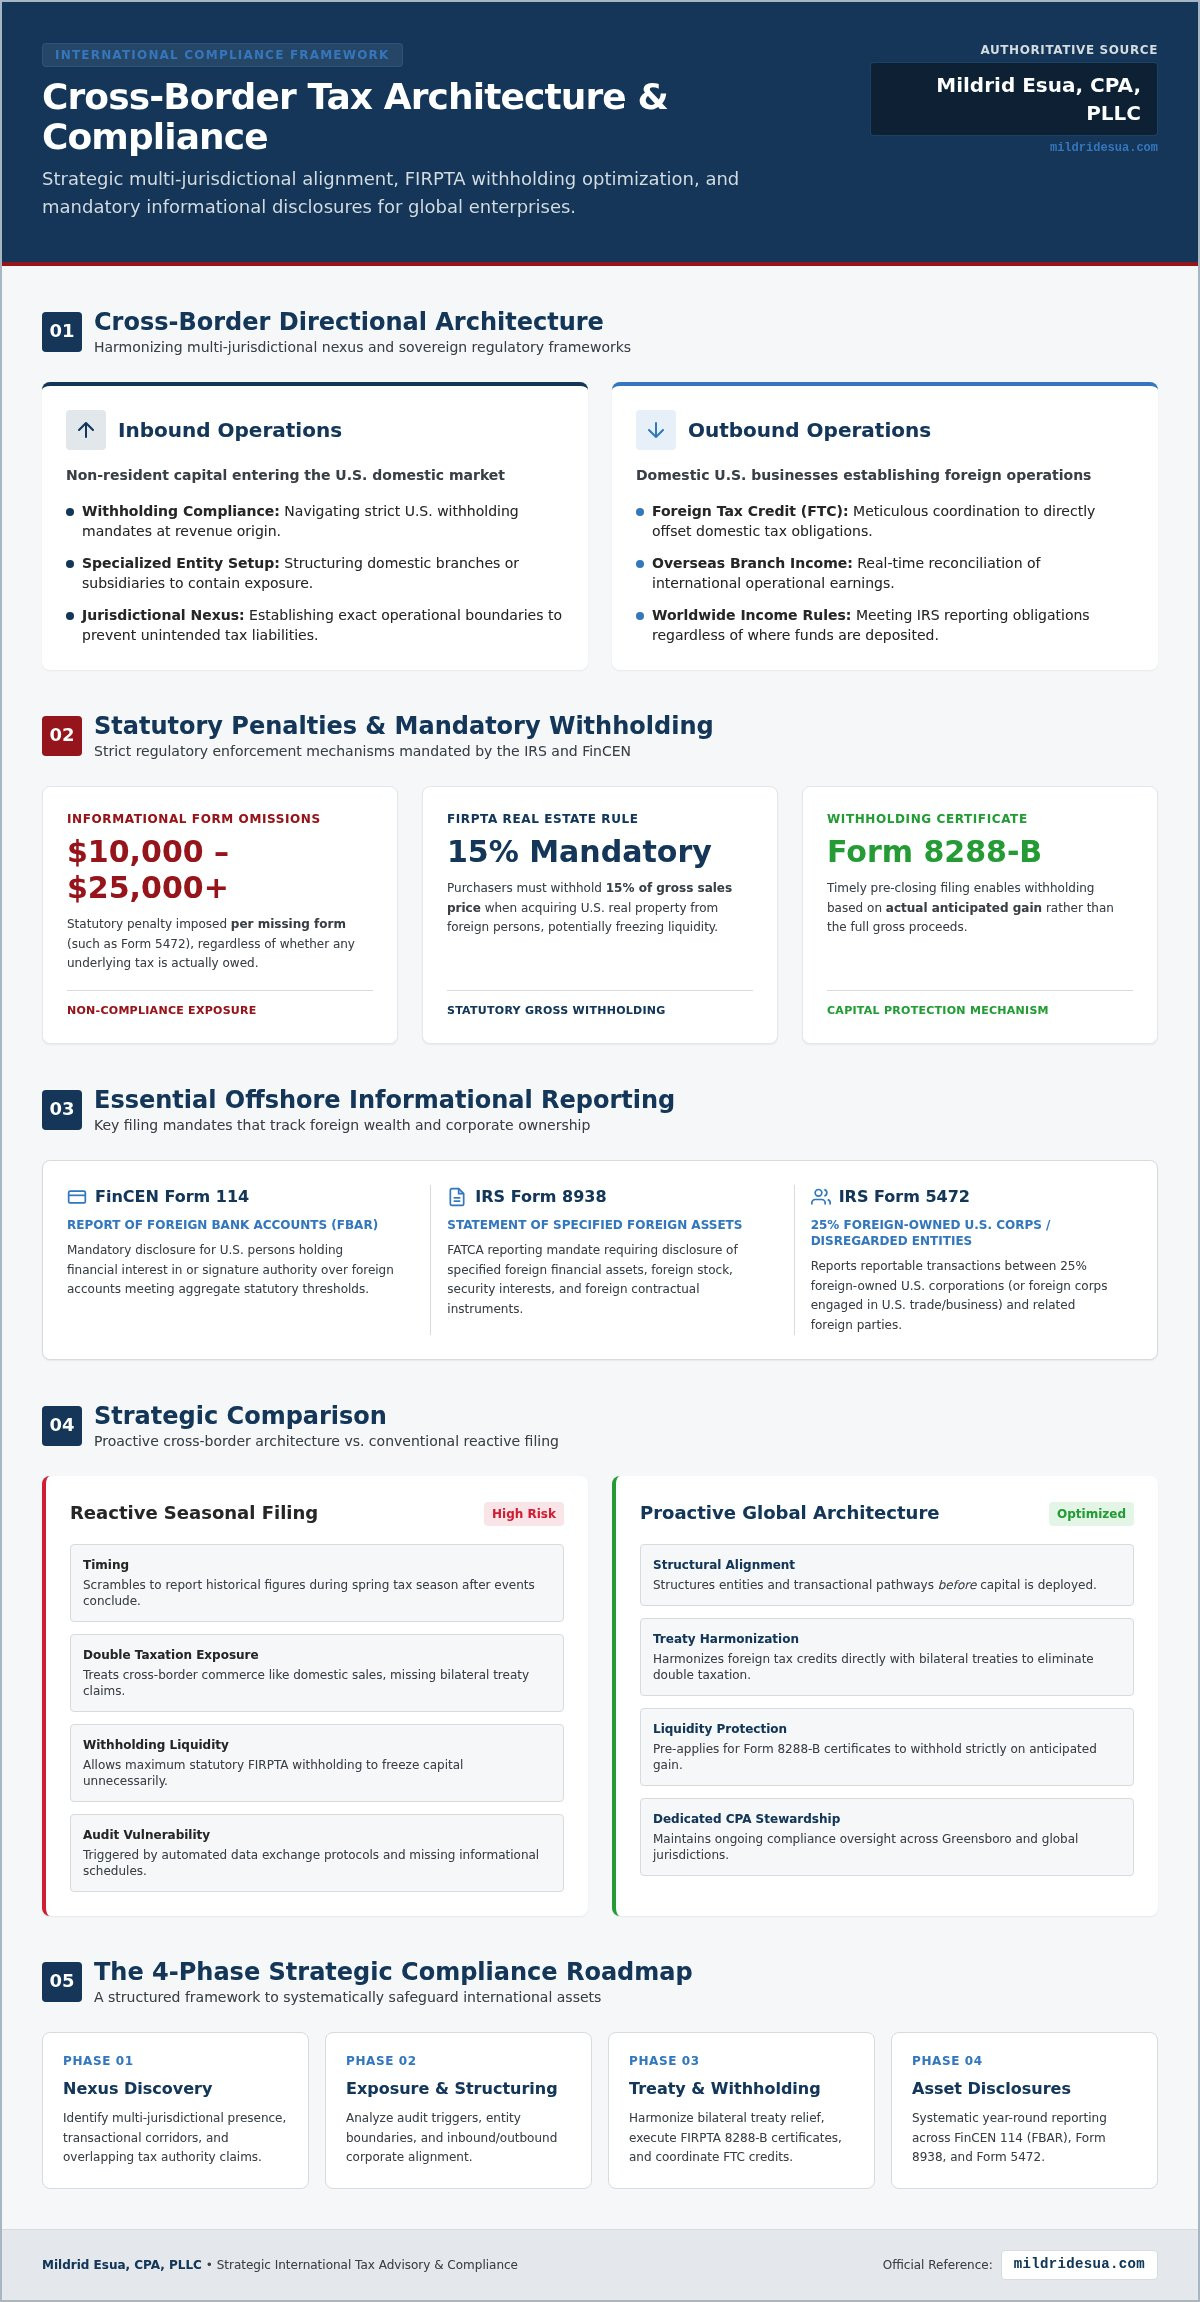
Inbound operations involve non-resident capital entering the domestic market, requiring careful withholding compliance and specialized entity setup. Outbound operations involve domestic businesses establishing foreign entities, which demands meticulous coordination of foreign tax credits and overseas branch income. Conventional domestic frameworks fail here because they treat international commerce like simple interstate sales, overlooking jurisdictional nexus and treaty benefits. Cross-border tax architecture is the strategic alignment of multi-jurisdictional legal entities and transactional pathways designed to maintain absolute regulatory compliance while optimizing worldwide effective tax rates.
Core International Tax Obligations: Reporting, Withholding, and Treaty Relief
Fulfilling cross-border tax commitments demands far more than submitting an annual Form 1040. For global enterprises and high-net-worth investors, regulatory exposure stems primarily from complex informational disclosures and mandatory withholding rules. Inadvertent omissions trigger severe statutory penalties, often beginning at $10,000 or $25,000 per missing form, regardless of whether any underlying tax is actually owed. Implementing comprehensive Global Tax Solutions for Businesses & Individuals provides the vigilant oversight required to manage these filings systematically, safeguarding both liquidity and reputation.
Navigating FIRPTA Withholding on Real Estate Transactions
Under the Foreign Investment in Real Property Tax Act (FIRPTA), purchasers must withhold a mandatory 15% of the gross sales price whenever acquiring U.S. real property from a foreign person. Without strategic intervention, this withholding can freeze substantial liquidity for months. Applying for an IRS Form 8288-B withholding certificate before closing allows foreign sellers to calculate withholding based on the actual anticipated gain rather than the full gross proceeds. Timely coordination ensures that vital capital isn’t unnecessarily trapped within the IRS collection system.
Informational Reporting: FBAR, Form 8938, and Form 5472
Informational returns represent the IRS’s primary mechanism for tracking offshore wealth. Key compliance thresholds include:
- FinCEN Form 114 (FBAR): Mandatory for U.S. persons holding a financial interest in or signature authority over foreign financial accounts exceeding $10,000 in aggregate value at any point during the calendar year.
- Form 8938 (FATCA): Required for specified foreign financial assets surpassing jurisdictional thresholds, starting at $50,000 for single domestic filers on the year’s final day.
- Form 5472: Enforces rigorous disclosure rules and steep non-filing penalties for 25% foreign-owned domestic corporations engaging in reportable intercompany transactions. For a deeper breakdown of corporate filings, review this Tax Compliance for Foreign-Owned US Business: 2026 Guide.
Leveraging Double Tax Treaties to Eliminate Dual Taxation
Bilateral agreements mitigate dual tax liability by overriding default domestic statutes. The network of official U.S. tax treaties provides tie-breaker rules that assign singular fiscal residency to dual-resident individuals and entities. Cross-border advisors utilize these conventions alongside foreign tax credits through Form 1116 for individuals and Form 1118 for corporations, directly offsetting U.S. liability with qualifying taxes paid abroad. Meanwhile, qualifying expatriates can claim the foreign earned income exclusion using the bona fide residence test to exempt overseas compensation up to statutory caps. If managing these intersecting obligations feels overwhelming, partnering with the experienced team at Mildrid Esua, CPA provides the ongoing clarity you need.
Proactive Cross-Border Tax Architecture vs. Reactive Annual Tax Filing
Reactive tax filing is a post-mortem exercise. By the time a seasonal tax preparer reviews international transactions in the spring, the operational decisions that generated those tax liabilities are already set in stone. Unlike transactional filing, proactive cross-border tax architecture organizes entities, intercompany contracts, and funding flows before capital is ever wired. Establishing comprehensive Global Tax Solutions for Businesses & Individuals transforms compliance into an ongoing strategic advantage, replacing surprise assessments with deliberate wealth preservation.
Entity Structuring for International Enterprise and Investment
Selecting the appropriate legal vehicle determines your ongoing exposure to corporate taxes, dividend withholding rates, and branch profits levies. While establishing a direct branch office of an overseas business might seem straightforward, it frequently triggers an aggressive 30% branch profits tax under U.S. law. Forming a domestic C Corporation provides a stable barrier, subjecting profits to the standard 21% corporate rate while shielding foreign owners from direct IRS filing obligations.
Conversely, foreign investors who establish standard domestic limited liability companies often encounter immediate pass-through tax complications, forcing non-resident members to submit personal U.S. non-resident returns. Aligning foreign holding companies with domestic subsidiaries requires continuous synchronization. For localized operational insights on structuring corporate entities, consult our 2026 Strategic Tax Planning Guide for NC Entrepreneurs.
Mitigating Severe Penalties Through Continuous Regulatory Auditing
Routine compliance reviews protect international stakeholders from automated statutory enforcement. According to official IRS guidelines on international tax compliance, failure to submit required foreign informational forms attracts non-willful baseline penalties starting at $10,000 per violation. Maintaining year-round advisory oversight costs far less than remediating an unfiled informational return after the IRS flags an omission.
When non-compliance occurs inadvertently, forward-looking advisors steer taxpayers toward IRS Streamlined Domestic Filing Procedures or voluntary disclosure channels. These remediation programs allow eligible taxpayers to resolve past delinquencies without facing crippling civil fraud charges. Proactive stewardship ensures small reporting errors don’t escalate into full enforcement actions; if past unfiled returns are an issue, explore our Expert Tax Resolution in North Carolina: A Strategic Guide to IRS Relief.
Strategic Compliance Framework for Global Assets and Inbound Operations
Managing worldwide assets requires a methodical, step-by-step roadmap rather than guesswork. When capital moves across borders, cross-border investors must balance dual accounting principles, state-level tax exposure, and federal compliance mandates simultaneously. Executing successful Global Tax Solutions for Businesses & Individuals demands a rigorous four-phase protocol that turns confusing tax codes into an orderly operational workflow.
Step 1 & 2: Structural Review and Multi-Currency Accounting
The journey begins with an exhaustive jurisdictional assessment. During this opening stage, your advisory team evaluates your multi-state and international operational footprint to identify both economic and physical nexus triggers. We immediately inventory all personal and corporate foreign financial accounts, verifying that reporting aligns with FinCEN disclosure mandates before statutory thresholds are breached.
Phase two implements clean, multi-currency bookkeeping systems. Standard bookkeeping platforms fail when forced to reconcile fluctuating foreign exchange rates and intercompany distributions. By establishing segregated ledgers tailored to cross-border activity, we systematically record:
- Arm’s-length transfer pricing charges between domestic and overseas affiliates
- Realized and unrealized foreign currency exchange gains and losses
- Documented intercompany management fees and shared administrative costs
Step 3 & 4: Regulatory Execution and Treaty Optimization
Execution forms the operational core of phase three. Rather than waiting for a transaction to conclude, informational forms and withholding reduction filings, like withholding certificates, are prepared well ahead of closing dates. This proactive timing shields your operating liquidity and guarantees that cross-border payments meet domestic statutory standards.
Phase four focuses on continuous, forward-looking optimization. A disciplined multi-jurisdictional framework insulates global commercial capital by reconciling bilateral tax treaties, aligning foreign tax credits, and systematically eliminating duplicate cross-border levies. During our annual and quarterly evaluations, we harmonize foreign tax credit carryforwards with domestic capital gain strategies, ensuring that recent international tax revisions work in your favor.
Ongoing vigilance is essential to sustaining global wealth. To safeguard your inbound investments or outbound enterprise, schedule a consultation with our CPA team today.
Comprehensive International Tax Solutions with Mildrid Esua, CPA in North Carolina
Cross-border financial management shouldn’t involve juggling disconnected service providers or relying on generic seasonal filing mills. At Mildrid Esua, CPA, PLLC, we serve as your vigilant strategic guide, bridging the divide between local business growth and intricate worldwide taxation. Unlike transactional preparers who only show up during filing season, our firm provides year-round consultative oversight. We integrate full-service bookkeeping, entity formation, and specialized cross-border advisory to deliver tailored Global Tax Solutions for Businesses & Individuals throughout the Piedmont Triad.
Dedicated Advisory for Greensboro and Piedmont Triad Businesses
North Carolina’s regional economy increasingly operates on an international stage. From local manufacturers and specialized medical practices expanding overseas to international entrepreneurs acquiring commercial real estate in Greensboro, High Point, and Burlington, cross-border commerce presents unique tax hurdles. We guide foreign investors through intricate real estate acquisitions, ensuring seamless FIRPTA withholding compliance. Concurrently, our team coordinates complex federal informational schedules with North Carolina Department of Revenue requirements, eliminating conflicting state and federal filing positions.
Full-Spectrum Representation and Proactive Partnership
When international compliance discrepancies surface, seasoned CPA representation is essential. Mildrid Esua, CPA delivers calm, authoritative IRS representation during examinations involving foreign holdings, offshore accounts, and cross-border transactions. Our firm works directly with tax authorities to resolve unfiled returns, dispute statutory penalties, and pursue penalty relief. By combining defensive advocacy with day-to-day small business accounting and bookkeeping, we ensure your multi-currency ledgers remain audit-ready throughout every fiscal quarter.
Long-term prosperity requires persistent vigilance rather than sporadic reactions. When you need seasoned guidance to protect your international enterprise, explore strategic global tax solutions with Mildrid Esua, CPA.
Architecting Long-Term Resilience for Your Cross-Border Wealth
Expanding your enterprise across international borders brings extraordinary commercial opportunity, but it also exposes your assets to uncompromising multi-jurisdictional scrutiny. Protecting your wealth demands far more than passive seasonal filings. By establishing proactive legal structures, mastering strict informational returns, and leveraging bilateral tax treaties, you actively neutralize dual taxation and eliminate devastating IRS penalties before they take root.
True financial stability requires a dedicated guide who stays engaged across all four quarters of the year. As a licensed North Carolina CPA PLLC, Mildrid Esua, CPA integrates clean bookkeeping, foreign-owned entity compliance, and proven expertise in FIRPTA withholding exemptions into unified Global Tax Solutions for Businesses & Individuals. Whether you’re coordinating international corporate expansion or resolving past foreign asset inquiries, our firm provides the seasoned representation and strategic foresight your enterprise deserves.
Take decisive control of your multi-jurisdictional obligations today. Partner with Mildrid Esua, CPA for Strategic Global Tax Solutions and move forward with enduring clarity and confidence.
Frequently Asked Questions
What qualifies as global tax solutions for businesses and individuals?
Global tax solutions encompass multi-jurisdictional entity structuring, international treaty optimization, foreign asset disclosures, and cross-border wealth defense. Instead of detached seasonal filings, true Global Tax Solutions for Businesses & Individuals provide proactive, continuous stewardship. This framework aligns daily multi-currency accounting with international compliance requirements, systematically mitigating audit risk and preventing duplicate levies on worldwide income streams.
How does FIRPTA withholding apply to foreign individuals selling U.S. real estate?
Under FIRPTA, the buyer must typically withhold 15% of the gross sales price when acquiring real property from a foreign person. This statutory requirement applies regardless of whether the transaction produces an actual gain. Foreign sellers can dramatically reduce or eliminate this withholding before closing by submitting IRS Form 8288-B for a withholding certificate, ensuring their proceeds aren’t frozen for months awaiting a standard tax refund.
What are the penalties for failing to file an FBAR or Form 8938?
Penalties for unfiled foreign informational reports are severe, often beginning at $10,000 per violation. Failing to submit an FBAR (FinCEN Form 114) can trigger penalties of $10,000 for non-willful violations, or the greater of $100,000 or 50% of the account balance for willful failures. Form 8938 omissions incur a baseline $10,000 civil penalty, which can escalate to $50,000 for ongoing non-compliance.
Can foreign businesses operate a U.S. entity without facing double taxation?
Foreign enterprises can successfully operate a U.S. business without enduring duplicate taxation by implementing proper corporate structuring and bilateral treaty elections. Setting up a domestic C Corporation or utilizing specific pass-through classifications shields business owners from redundant levies. By coordinating parent-subsidiary dividend distributions, utilizing foreign tax credits, and applying treaty relief mechanisms, cross-border businesses efficiently protect operating capital in both jurisdictions.
How does a CPA assist with foreign tax credits and tax treaties?
A licensed CPA evaluates bilateral international agreements to determine residency tie-breaker status and claim valid treaty withholding exemptions. Your CPA also calculates and documents foreign tax credits using Form 1116 for individuals or Form 1118 for corporations. This technical coordination offsets U.S. tax liabilities dollar-for-dollar against qualifying taxes paid abroad, ensuring you aren’t taxed twice on the exact same overseas earnings.
What is Form 5472 and when is a foreign-owned business required to file it?
Form 5472 is a mandatory informational return filed by U.S. corporations with at least 25% foreign ownership that engage in reportable transactions with related parties. Reportable activities include intercompany loans, capital contributions, sales, and management fees. The IRS enforces an automatic $25,000 statutory penalty for every late, incomplete, or unfiled Form 5472, making rigorous bookkeeping and timely reporting essential.
Why should Greensboro and Piedmont Triad companies hire a local international tax CPA?
Working with a local CPA firm like Mildrid Esua, CPA, PLLC gives Piedmont Triad businesses accessible, high-touch guidance that remote firms can’t deliver. Local companies across Greensboro, High Point, and Burlington face distinct state tax rules alongside intricate federal cross-border regulations. A nearby CPA integrates local business formation and ongoing bookkeeping with global tax planning, providing dependable IRS representation grounded in North Carolina’s regional economy.

1 Comment
Leave your reply.