

According to research from CPA Trendlines, nearly 13% of entrepreneurs facing bankruptcy cite unmanageable tax problems as a direct cause of their company’s failure. When back taxes accumulate and automated IRS collection notices begin arriving, securing legitimate tax relief for small business owners becomes an immediate operational priority rather than a deferred administrative task.
Watching crippling self-employment obligations drain critical cash flow while dreading the arrival of an unexpected bank levy or federal tax lien is exhausting. You aren’t alone if years of disorganized financial records have created deep uncertainty about what you actually owe, leaving you feeling vulnerable to escalating enforcement action.
Unlike reactive quick fixes that merely delay collections, this guide details actionable federal and state strategies to halt IRS enforcement, negotiate manageable repayment structures, and permanently minimize liabilities. You’ll explore verified 2026 debt resolution programs alongside proactive accounting systems designed to eliminate back debt and protect your enterprise for the long haul.
Key Takeaways
- Learn how genuine tax relief for small business owners moves beyond reactive damage control by pairing IRS debt resolution with proactive tax planning.
- Discover the financial disclosure standards required to secure statutory IRS settlements, structured installment agreements, and penalty abatements.
- Uncover structural tax strategies, such as an S Corp election, designed to permanently minimize self-employment tax exposure and protect operating cash flow.
- Follow a sequential five-step roadmap that prioritizes immediate compliance actions to halt aggressive IRS enforcement before entering negotiations.
- Understand the distinct strategic advantage of working with a licensed CPA who provides ongoing stewardship rather than transactional resolution mills.
Understanding Tax Relief for Small Business Owners: Emergency Resolution vs. Proactive Planning
Genuine tax relief for small business owners is not merely an emergency negotiation with federal collectors. Broadly defined, it combines administrative debt resolution, such as structured settlements or penalty abatements, with forward-looking structural tax restructuring. Reactive crisis management treats the symptom by scrambling to pause a collection notice; proactive tax advisory cures the underlying cause, establishing permanent operational stability across your enterprise.
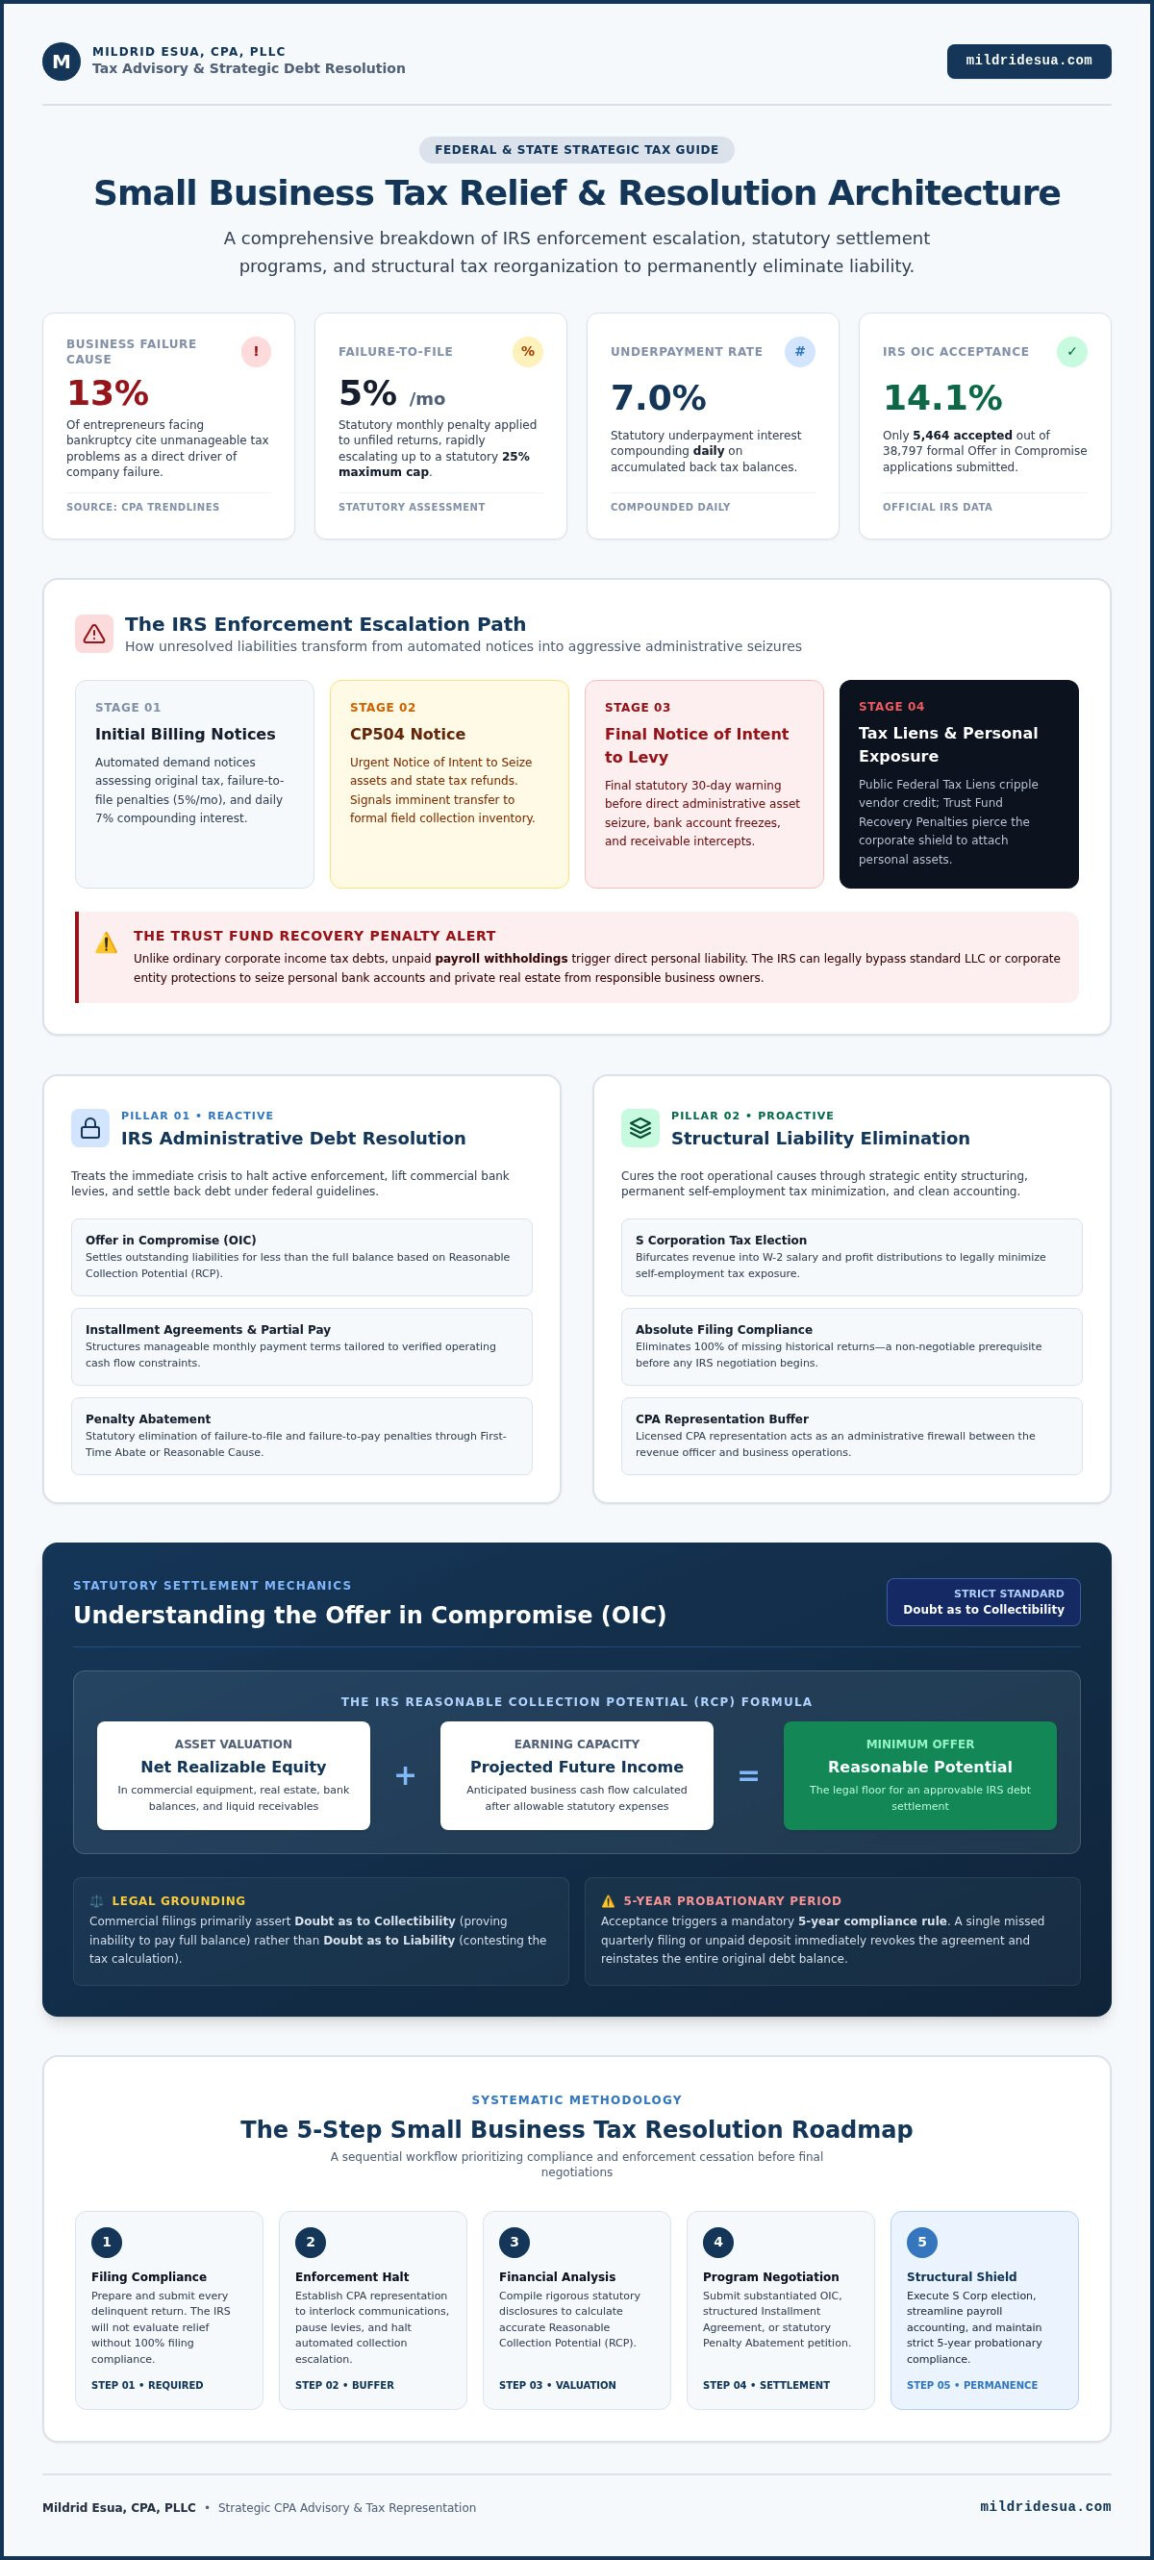
Left unaddressed, statutory assessments escalate rapidly. In 2026, the failure-to-file penalty adds 5% per month up to a 25% cap, while underpayment interest compounds daily at 7%. Before you can negotiate options like the Offer in Compromise (OIC) program or an installment agreement, the IRS requires absolute compliance. Every missing tax return must be completed and filed before authorities consider any formal settlement relief.
To better understand how federal tax legislation shapes small business savings and liability planning, watch this helpful overview:
The True Scope of Small Business Tax Liabilities
Small business debts generally fall into two distinct categories: standard pass-through income liabilities and payroll trust fund obligations. While unpaid self-employment taxes drain monthly operating cash flow, payroll withholdings present a far graver risk. Under the Trust Fund Recovery Penalty, the IRS can bypass standard corporate entity shields to hold business owners personally liable for withheld employee taxes, placing personal bank accounts and private real estate squarely in jeopardy.
The High Cost of Delay: IRS Enforcement Escalation
Ignoring administrative notices accelerates statutory enforcement. The collection cycle moves deliberately from initial billing statements to a CP504 notice, culminating in a Final Notice of Intent to Levy. A filed Notice of Federal Tax Lien alerts creditors, immediately freezing commercial banking relationships and crippling supplier terms. Retaining an expert tax resolution North Carolina CPA establishes a professional buffer, stepping between your business and revenue officers to halt aggressive enforcement while crafting a sustainable resolution path.
Official IRS Tax Relief Programs: Practical Debt Resolution Options
Securing statutory debt resolution demands strategic preparation rather than blind optimism. National resolution mills routinely market exaggerated promises of settling debts for pennies on the dollar, yet official IRS data shows that in 2025, the agency accepted just 5,464 Offers in Compromise out of 38,797 applications. Securing legitimate tax relief for small business owners depends entirely on rigorous financial disclosures, statutory formulas, and substantiated evidence.
Offer in Compromise (OIC) for Operating Businesses
An Offer in Compromise allows viable enterprises to settle outstanding tax liabilities for less than the full amount owed. Most commercial filings proceed under Doubt as to Collectibility, asserting that the company cannot realistically pay the balance in full, rather than challenging the assessment under Doubt as to Liability. According to official IRS guidance on Offers in Compromise, the agency computes your Reasonable Collection Potential by evaluating net realizable equity in business assets combined with projected future income. Accepting an OIC requires strict adherence to all filing and payment obligations during a mandatory five-year probationary period; a single missed deadline revokes the agreement and reinstates the original debt.
Installment Agreements and Partial Pay Structures
When an outright settlement isn’t mathematically viable, formal installment structures protect your operating cash flow. While standard streamlined agreements resolve balances quickly without extensive documentation, higher corporate tax debts demand customized, non-streamlined payment plans backed by detailed cash-flow statements. For enterprises experiencing sustained financial contraction, a Partial Payment Installment Agreement (PPIA) allows you to pay a reduced monthly amount based on verifiable disposable income. These plans require routine financial reviews, but they freeze aggressive collection activity while your business stabilizes.
Penalty Abatement and Currently Not Collectible (CNC) Status
Penalties often represent up to a third of an outstanding tax bill. Qualified businesses can remove failure-to-file and failure-to-pay penalties using administrative First-Time Abatement waivers or by demonstrating reasonable cause, such as natural disasters, sudden banking crises, or serious partner illness. If operational cash flow is entirely depleted, securing Currently Not Collectible (CNC) status temporarily pauses all bank levies and asset seizures without extinguishing the underlying liability. When facing mounting enforcement, partnering with a dedicated tax resolution advisor ensures your financial disclosures accurately represent your actual collection potential.
Structural Tax Relief: Eliminating Future Tax Liabilities Before They Arise
Settling an existing tax balance resolves the past, but true financial freedom requires redesigning your operational foundation. Enduring tax relief for small business owners isn’t found in perpetual negotiations with revenue officers; it’s engineered through forward-looking structural planning. Implementing proactive entity strategies, accelerating statutory deductions, and maintaining clean financial records transform tax compliance from a perennial emergency into a predictable operational discipline. Exploring strategic tax planning for businesses allows leadership to preserve hard-earned working capital and build sustainable enterprise value.
S Corporation Election to Reduce Self-Employment Taxes
Sole proprietors and single-member LLCs face a 15.3% self-employment tax on their entire net business profit. Electing S Corporation tax status provides immediate structural relief by bifurcating earnings into W-2 wages and shareholder distributions. Because distributions escape self-employment assessments, this structure yields significant ongoing tax savings. However, owner-operators must establish defensible reasonable compensation benchmarks grounded in verifiable industry wage data to withstand IRS scrutiny. Following a dedicated roadmap for the S Corp election for self employment tax ensures timely election filings and defensible payroll implementation.
Maximizing Section 179 and Qualified Business Income Deductions
Proactive restructuring capitalizes on powerful statutory deductions to drive down adjusted gross business income:
- Section 179 and Bonus Depreciation: The Section 179 expensing cap allows eligible enterprises to deduct up to $2,560,000 in qualifying capital equipment investments for 2026, reinforced by permanent 100% bonus depreciation rules.
- Section 199A QBI Deduction: The permanent 20% Qualified Business Income deduction allows qualified pass-through business owners to deduct up to one-fifth of their net operating earnings directly from taxable income.
Accurate Bookkeeping as the Primary Shield Against Audits
Disorganized ledgers remain the primary trigger for catastrophic audit assessments. When revenue agents initiate an examination, unsubstantiated deductions and commingled accounts are immediately disallowed, retroactively manufacturing an artificial tax liability loaded with negligence penalties. Retaining dedicated monthly bookkeeping for small businesses preserves real-time receipts, reconciles commercial transactions, and insulates personal accounts. Systematic accounting provides the rock-solid evidentiary trail necessary to defend your deductions, safeguarding genuine long-term tax relief.
Step-by-Step Roadmap to Resolving Small Business Tax Controversies
Facing aggressive collection letters creates paralyzing friction for executive leadership. Moving from financial chaos to sustainable resolution requires a methodical framework rather than ad hoc responses. Securing lawful tax relief for small business owners follows an exacting administrative sequence designed to halt aggressive enforcement, substantiate economic reality, and bind the IRS to manageable terms.
Step 1 & 2: Halting Enforcement and Filing Delinquent Returns
The resolution process begins with an immediate enforcement hold. Authorized representation allows your advocate to contact collection personnel directly, requesting a 30- to 60-day collection stay while financial records are reconstructed. During this window, you must prepare and submit all delinquent business and personal returns. Filing original returns promptly replaces any IRS Substitute for Return (SFR) assessments. Because SFR assessments calculate taxes using gross income without granting valid operational deductions, filing true returns immediately reduces the baseline balance.
Step 3: Comprehensive Financial Analysis via Form 433-B
Once compliance is restored, commercial debtors must document their financial position using IRS Form 433-B (Collection Information Statement for Businesses). This critical diagnostic requires detailed substantiation across multiple operational areas:
- Asset Valuation: Itemizing liquid accounts, equipment equity, and accounts receivable aging schedules discounted for collectibility.
- Cash Flow Modeling: Reconciling gross receipts against IRS allowable operational expenses while eliminating disallowable discretionary costs.
- Economic Reality: Establishing an unassailable financial portrait that proves full payment would cause severe commercial impairment.
Step 4 & 5: Selecting the Program and Executing the Agreement
With clean financial data established, you can target the resolution program that matches your cash flow, whether through a structured installment arrangement, non-collectible status, or formal liability compromise. Once the proposal package is submitted with supporting legal arguments, negotiations shift to the Revenue Officer or settlement officer assigned to the file. Following formal acceptance, maintaining flawless ongoing compliance is mandatory. Making timely federal tax deposits and quarterly estimated payments protects the agreement, ensuring negotiated relief remains permanent. If revenue officers are demanding immediate compliance, schedule an IRS representation consultation to take control of the collection process today.
Why Partnering with a Local CPA Firm Ensures Lasting Tax Relief
National resolution telemarketing companies treat tax debt as a high-volume transactional commodity. They route distressed business owners through rotating customer service representatives who possess little understanding of local commercial markets or state regulatory authorities. In sharp contrast, securing authentic tax relief for small business owners demands vigilant, customized stewardship from a licensed professional who remains accountable long after initial filings are complete.
Direct Representation Under Form 2848 Power of Attorney
Executing IRS Form 2848 (Power of Attorney and Declaration of Representative) establishes an immediate statutory shield between your enterprise and collection personnel. Once on file, IRS revenue officers and state collection agents are legally required to communicate exclusively with your representative. This direct buffer delivers tremendous operational peace of mind:
- Eliminates High-Pressure Interrogations: Revenue officers often probe for admissions regarding accounts receivable and discretionary expenses. A CPA controls all dialogues, preventing accidental disclosures that damage settlement terms.
- Enforces Agency Accountability: Experienced representation ensures tax authorities strictly adhere to the Internal Revenue Manual, immediately challenging premature levies, flawed notices, or lapsed statutory deadlines.
- Removes Daily Distractions: Transferring collection calls, formal documentation summonses, and audit conferences to your advocate allows you to focus fully on day-to-day enterprise operations.
Integrated Accounting, Resolution, and Forward Tax Architecture
Unlike automated software services or standalone resolution boiler rooms, a local CPA practice bridges historical controversy with forward-looking structural strategy. Resolving a federal tax delinquency while ignoring concurrent state liabilities guarantees future failure; state revenue agencies often move faster than the IRS to freeze commercial operating accounts. Mildrid Esua, CPA, PLLC integrates back tax resolution, monthly bookkeeping, payroll compliance, and proactive entity structuring under a single advisory umbrella. For businesses across Greensboro, High Point, and Burlington, this cohesive partnership transforms unfiled returns and tax liens into lasting financial stability.
Reclaim Enterprise Stability Through Strategic Tax Stewardship
Resolving severe tax debt requires balancing urgent enforcement defense with deliberate structural design. Authentic tax relief for small business owners goes well beyond temporary collection holds. It demands establishing disciplined accounting systems, correcting delinquent returns, and proactively restructuring your entity to permanently curb crippling liabilities.
As a licensed Certified Public Accountant with specialized IRS representation authority, Mildrid Esua, CPA, PLLC serves as a vigilant advocate for entrepreneurs throughout Greensboro, High Point, and the greater Piedmont Triad. We don’t rely on impersonal call centers or generic promises. Instead, our firm integrates forensic bookkeeping, payroll resolution, and statutory defense directly on your behalf, shielding your enterprise from aggressive collection action while positioning your business for sustainable profitability.
You don’t have to face federal and state revenue officers alone. Take decisive control of your company’s future and schedule a confidential tax consultation with Mildrid Esua, CPA today. Lasting financial clarity is entirely within your reach.
Frequently Asked Questions
Can the IRS shut down my business for unpaid payroll taxes?
Yes, the IRS possesses the statutory power to seize commercial assets, padlock facilities, and force closure for unresolved payroll tax delinquency. Trust fund taxes represent fiduciary money withheld from employee paychecks, so federal collectors treat non-remittance as severe non-compliance. If a business repeatedly skips Form 941 deposits, revenue officers can escalate toward business closure. Retaining licensed representation immediately halts aggressive enforcement, keeping your doors open while establishing a structured resolution.
What is the difference between an Offer in Compromise and an Installment Agreement?
An Offer in Compromise settles an outstanding tax balance for less than the total amount owed, whereas an Installment Agreement establishes a structured plan to pay the liability over monthly installments. Compromise filings demand detailed proof that full collection is mathematically impossible based on your asset equity and disposable cash flow. Installment plans keep working capital intact while maintaining operating solvency. Both mechanisms offer proven paths to achieve statutory tax relief for small business owners.
How do unfiled business tax returns impact my eligibility for tax relief?
Unfiled tax returns immediately disqualify an enterprise from entering formal settlement negotiations or binding administrative repayment plans. The IRS enforces strict baseline compliance before reviewing penalty abatements or compromise agreements. Unfiled periods also trigger automated substitute returns, which deliberately omit business deductions and inflate your assessed balance. Reconstructing past books and submitting accurate original returns must occur before revenue officers will negotiate any relief option.
Can personal assets be seized to pay for business tax debts?
Yes, personal assets can be seized if you operate as a sole proprietorship or if your company accrued unpaid payroll withholdings. Unincorporated owners carry direct personal liability for all commercial tax liabilities. Even within incorporated entities, the IRS routinely enforces the Trust Fund Recovery Penalty against business owners, officers, and financial managers. This personal assessment allows collection officers to levy private bank accounts, real estate, and personal investments.
What qualifies a small business for IRS First-Time Penalty Abatement?
A small business qualifies for First-Time Abatement if it holds a clean compliance record with no prior penalties on that specific tax form for the preceding three tax years. The enterprise must also have filed all currently due returns and paid or arranged to pay any outstanding balances. This administrative relief waives failure-to-file and failure-to-pay penalties quickly without requiring lengthy legal documentation of economic hardship.
How long does the IRS have to collect back taxes from a business?
The IRS generally has ten years from the official tax assessment date to collect outstanding balances before the statutory collection window expires. This timeline is called the Collection Statute Expiration Date. Specific administrative actions, such as submitting an Offer in Compromise, requesting Collection Due Process hearings, or entering bankruptcy, temporarily suspend and extend this window. A seasoned CPA evaluates official tax transcripts to verify exact statutory deadlines.
Why should I choose a local CPA over a national tax relief company?
A local CPA provides direct, licensed accountability rather than routing your file through high-pressure telemarketing mills and anonymous customer service reps. Mildrid Esua, CPA, PLLC resolves federal IRS debt while concurrently addressing North Carolina Department of Revenue compliance for firms across Greensboro, High Point, and Burlington. This cohesive approach pairs tax relief for small business owners with ongoing forensic bookkeeping and entity planning, protecting your long-term stability.

Leave a Reply
Your email is safe with us.