

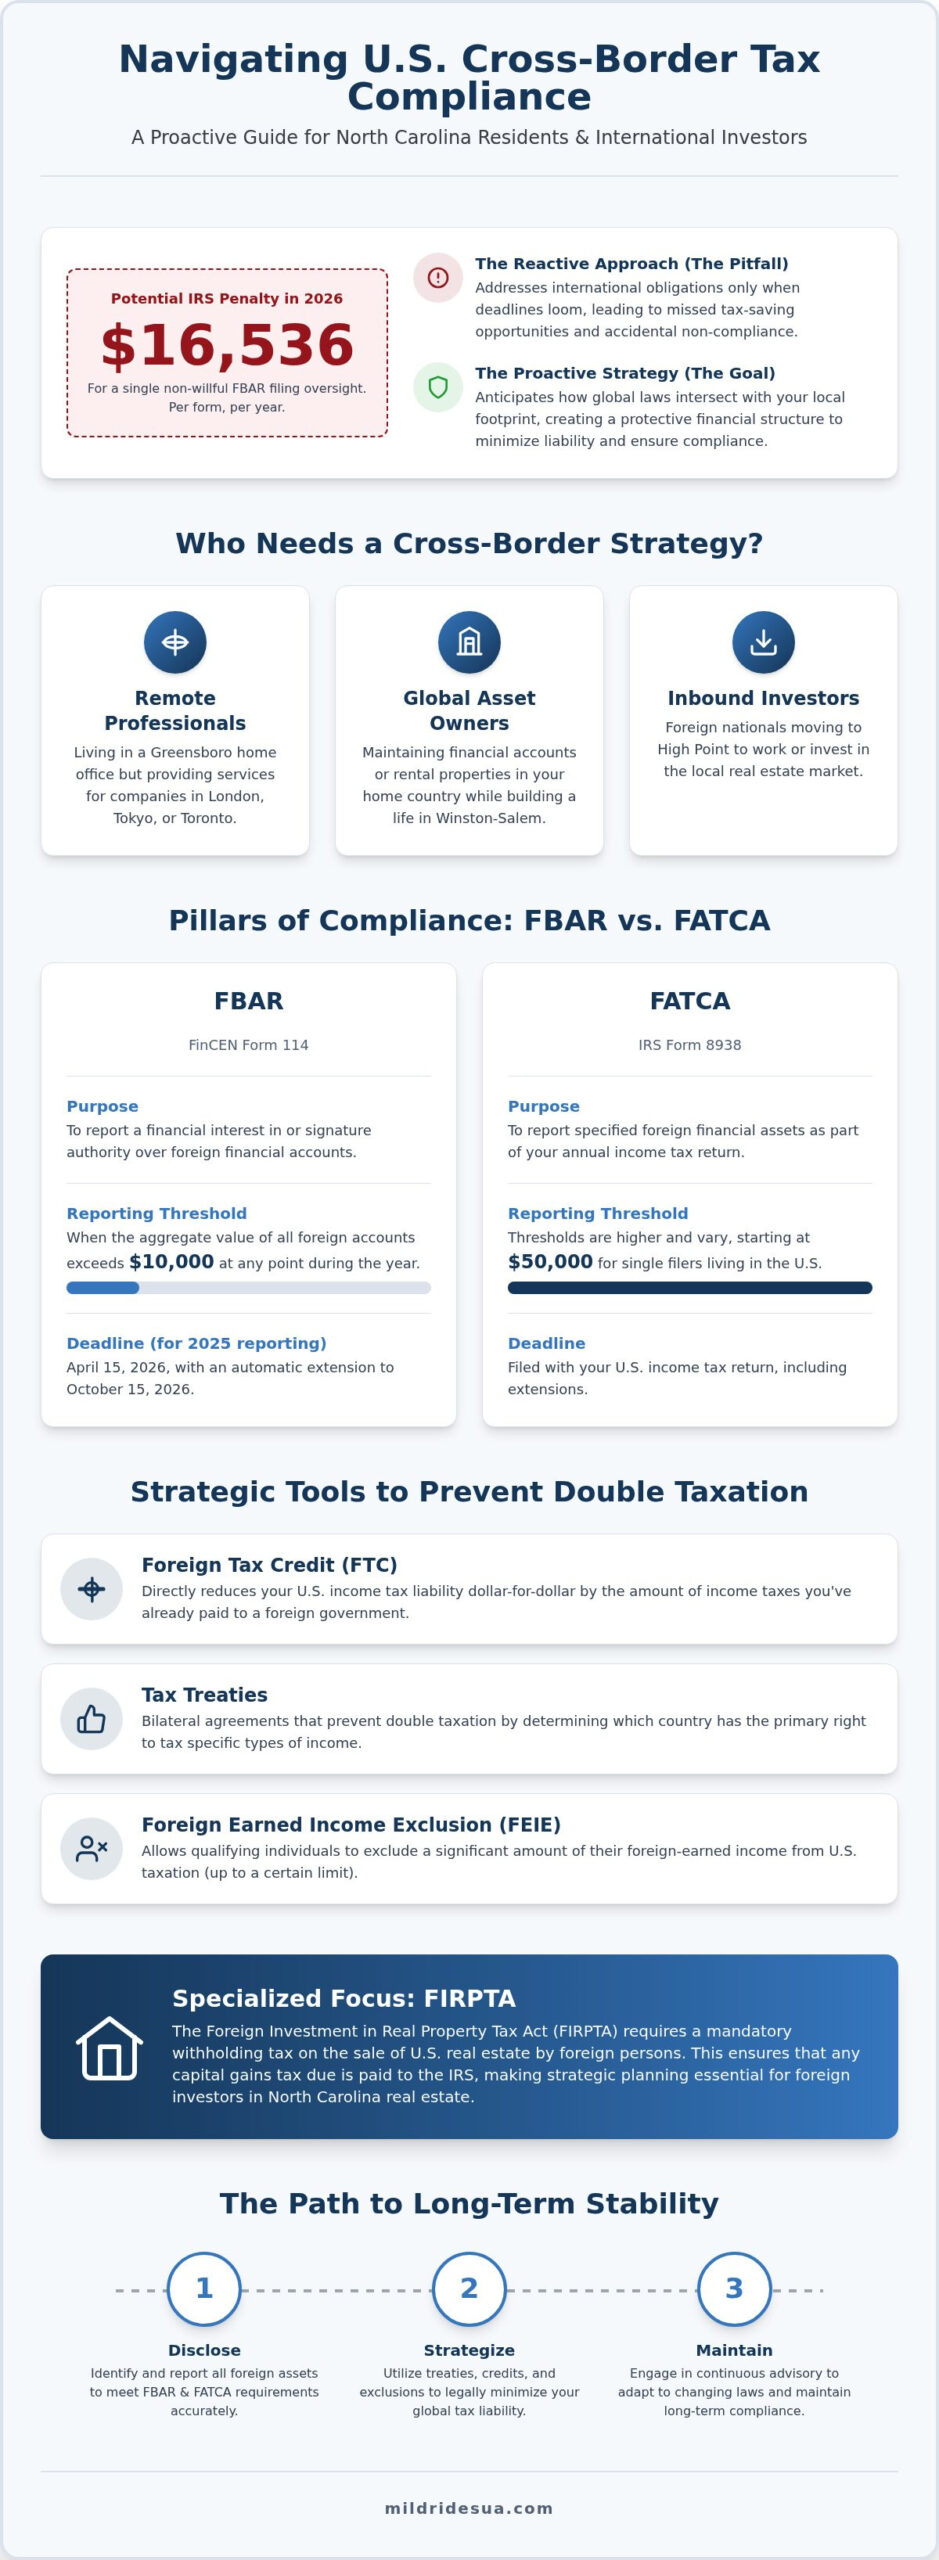
A single non-willful oversight on an FBAR filing in 2026 can now result in an IRS penalty of up to $16,536 per form. For many residents, this reality transforms international expansion from a milestone into a source of constant regulatory anxiety. Effective cross-border tax planning North Carolina requires more than just reactive annual filing; it demands a proactive architecture that anticipates global shifts before they impact your financial stability.
It’s natural to feel frustrated when you’re paying tax twice on the same dollar or confused by the dense language of modern tax treaties. You want the peace of mind that comes from knowing your foreign assets are reported correctly and your global liability is minimized. This guide provides a clear roadmap for managing the 2026 compliance landscape, ensuring you meet every FBAR and FATCA threshold without sacrifice. We’ll outline essential reporting requirements, explore strategic treaty applications, and demonstrate how vigilant stewardship protects your interests from unnecessary IRS scrutiny.
Key Takeaways
- Implement a proactive framework for cross-border tax planning North Carolina to protect your assets while navigating the unique tax obligations of the Greensboro and Winston-Salem regions.
- Identify critical reporting thresholds for FBAR and FATCA to ensure full disclosure of foreign financial assets and avoid escalating IRS penalties.
- Utilize strategic mitigation tools like the Foreign Tax Credit and Foreign Earned Income Exclusion to shield your income from being taxed twice across different jurisdictions.
- Master the FIRPTA withholding process to manage the financial implications of foreign investment in North Carolina real estate with precision.
- Transition toward a model of continuous advisory engagement to resolve past filing errors and maintain long-term stability in an increasingly complex global landscape.
Navigating the Complexity of Cross-Border Tax Planning in North Carolina
Cross-border tax planning North Carolina isn’t merely about checking boxes on an annual return; it’s the meticulous architecture of your financial life across international borders. Strategic planning involves the deliberate management of tax liabilities across multiple jurisdictions to ensure that your global growth isn’t stifled by redundant taxation or compliance failures. Unlike a reactive approach that focuses on past transactions, a proactive strategy anticipates how international laws intersect with your local footprint.
A traditional reactive filer often addresses international obligations only when a deadline looms, which frequently leads to missed opportunities for credits or accidental non-compliance. A strategic architect, however, views global assets as a cohesive system. By aligning your North Carolina business interests with international regulations, you create a protective barrier against the volatility of shifting tax codes. This vigilant stewardship ensures that every dollar earned abroad is optimized for your long-term stability here at home.
To better understand how residency and reporting impact your strategy, watch this helpful video:
A critical component of this architecture is understanding tax residency. This concept is distinct from your immigration status or visa type. The IRS often considers you a resident for tax purposes based on the substantial presence test, which counts the days you’ve spent in the U.S. over a three year period. When your residency status overlaps with another country, Tax Treaties serve as the primary tool to determine which nation has the first right to tax your income, preventing a scenario where you’re caught between two competing authorities.
Why North Carolina Residents Need International Strategy
The Piedmont Triad has become a significant hub for international activity, meaning cross-border tax planning North Carolina is no longer reserved for large corporations. You might require a specialized strategy if you fall into these common categories:
- Remote Professionals: You live in a Greensboro home office but provide services for a company based in London, Tokyo, or Toronto.
- Global Asset Owners: You maintain financial accounts or rental properties in your home country while building a life in Winston-Salem.
- Inbound Investors: You’re a foreign national who has moved to High Point for work or to invest in the local real estate market.
The Cost of Inaction: IRS Penalties and Double Taxation
Ignoring the nuances of international reporting carries heavy financial weight. For penalties assessed in 2026, a non-willful failure to file an FBAR can cost you up to $16,536 per form. Without a clear roadmap, you also risk double taxation, where the same dollar is taxed by both the U.S. and a foreign government. Our role is to act as a vigilant guide, identifying these risks early and implementing structures that ensure your global income remains a source of growth rather than a liability.
The Pillars of Compliance: FBAR, FATCA, and Tax Treaties
Compliance isn’t a suggestion; it’s a structural requirement for global financial health and effective cross-border tax planning North Carolina. For residents with international interests, the first pillar is FinCEN Form 114, commonly known as the FBAR. You must file this if the aggregate value of your foreign financial accounts exceeds $10,000 at any point during the calendar year. The deadline for your 2025 activity is April 15, 2026, though an automatic extension to October 15, 2026, provides a small window for those who act with foresight.
The second pillar is the Foreign Account Tax Compliance Act, or FATCA. While FBAR focuses on bank accounts, FATCA requires the disclosure of a broader range of foreign financial assets via Form 8938. For a single filer living in the U.S., the threshold begins at $50,000 on the last day of the year or $75,000 at any point during the year. Reviewing the official FATCA Reporting for U.S. Taxpayers summary reveals how these requirements often overlap with FBAR, creating a dual reporting burden that demands constant attention.
FBAR vs. FATCA: Understanding the Critical Differences
It’s a common misconception that filing one satisfies the other. FBAR is a Treasury Department requirement focused on law enforcement and money laundering prevention. FATCA is an IRS requirement focused on tax revenue and identifying tax evasion. Missing both forms doesn’t just result in double the paperwork; it can lead to catastrophic financial consequences. With non-willful penalties now reaching $16,536 per form, the cost of a simple administrative error is too high to ignore.
Leveraging Tax Treaties for NC Residents
Sophisticated cross-border tax planning North Carolina utilizes bilateral agreements to protect your income from being taxed twice. These treaties are vital for managing foreign pension distributions and social security benefits, which are often subject to complex withholding rules. You must also account for the Savings Clause, a standard treaty feature that allows the U.S. to tax its citizens as if the treaty didn’t exist. Our role as your guide is to find the specific exceptions and credits that still apply, ensuring you don’t overpay for your global success.
Stability in international finance is built on the foundation of accurate bookkeeping. Without granular records of every foreign transaction, applying for treaty benefits or satisfying IRS scrutiny becomes impossible. If you’ve discovered past reporting gaps, seeking tax resolution in North Carolina can rectify these errors before the IRS initiates an audit. Proactive management today prevents the high-stakes crises of tomorrow.
Strategic Tax Mitigation: Preventing Double Taxation for NC Businesses
For an entrepreneur in Greensboro or Winston-Salem, global expansion brings the immediate threat of double taxation. Effective cross-border tax planning North Carolina transforms this threat into a manageable variable by utilizing specific IRS mechanisms designed to prevent the same income from being taxed by two different countries. Unlike standard domestic accounting, international strategy requires you to choose between direct credits and income exclusions, a decision that dictates your long-term global tax liability.
This choice isn’t merely administrative; it’s a foundational part of your business architecture. Selecting the wrong mitigation tool can lead to thousands of dollars in lost liquidity. As a vigilant guide, we focus on identifying the most efficient path for your specific income structure, ensuring that your international growth remains a source of strength rather than a financial drain.
The Foreign Tax Credit (FTC) Strategy
The FTC is a primary tool for those operating in jurisdictions with high tax rates. It provides a dollar-for-dollar reduction in your U.S. tax liability based on the taxes you’ve already paid to a foreign government. We define the FTC as a mechanism to ensure the same dollar isn’t taxed twice, acting as a safeguard for your international profit margins. To maximize this benefit, you must strategically allocate credits into different “baskets,” such as general or passive income, to prevent credits from one category from being trapped and unused.
This level of foresight is a hallmark of strategic tax planning for businesses, ensuring your local NC operations aren’t subsidizing foreign tax obligations. Proper allocation requires granular bookkeeping and a deep understanding of how the IRS views foreign levies, particularly as North Carolina’s own corporate tax rate continues its scheduled decrease to 2.00% in 2026.
Foreign Earned Income Exclusion (FEIE) for Expats
For North Carolina residents living abroad, the FEIE offers a different path by allowing you to exclude a significant portion of your foreign earnings from U.S. taxation. To qualify, you must meet either the Physical Presence Test or the Bona Fide Residence Test, which requires rigorous documentation of your time spent outside the U.S. While the FEIE can simplify your return, it might be less beneficial than the FTC if you’re living in a high-tax country where the direct credit would yield a higher total savings.
It’s also vital to consider how these federal elections impact your North Carolina state tax obligations. Since NC uses federal Adjusted Gross Income as a starting point, these exclusions often flow through to your state return, but specific local adjustments may still apply. Beyond income, specialized rules like FIRPTA Withholding also come into play for those managing real estate assets, requiring a vigilant guide to navigate the intersection of property and income reporting. Making an informed choice between these tools ensures your business remains competitive on the global stage.
Specialized Planning: FIRPTA and Foreign Investment in NC Real Estate
Selling real estate in the Piedmont Triad as a foreign national involves a unique set of IRS hurdles, primarily governed by the Foreign Investment in Real Property Tax Act (FIRPTA). Unlike domestic sellers who receive their full proceeds at closing, foreign sellers are generally subject to a standard 15% withholding on the gross sales price. This isn’t a final tax; it’s a security deposit held by the IRS to ensure compliance. For many in the Greensboro and High Point markets, this withholding can exceed the actual gain on the property, creating an immediate liquidity crisis during a transaction.
Navigating this complexity requires more than just a real estate agent. Engaging a specialized FIRPTA withholding accountant is essential to ensure that your funds aren’t unnecessarily trapped by the federal government. Effective cross-border tax planning North Carolina focuses on reconciling these withholding requirements with your actual tax liability, allowing you to retain more of your equity at the point of sale.
Reducing the FIRPTA Withholding Burden
The most effective strategy to mitigate the 15% withholding is obtaining a Withholding Certificate from the IRS. This document allows for a reduction or total elimination of the withholding if you can prove that your “Maximum Tax Liability” is less than the standard 15%. This calculation is a vital component of cross-border tax planning North Carolina, as it prevents the IRS from holding excess capital that could be better utilized for your next investment. This calculation accounts for your original purchase price, improvements made to the property, and selling expenses. You must submit this application on or before the date of closing. The IRS typically takes 90 days or more to process these requests, so early intervention is a cornerstone of our proactive methodology.
Compliance for Foreign Investors in NC Property
Ownership doesn’t end at the purchase. If you’re a foreign investor holding rental properties in North Carolina, you must report that income annually on Form 1040-NR. To do this, you’ll need an Individual Taxpayer Identification Number (ITIN), which serves as your primary identifier for all U.S. tax matters. We also focus on long-term capital gains planning, ensuring that when you eventually divest from the NC market, your cost basis is documented correctly to minimize your final bill. If you’re ready to secure your real estate interests, partner with our Greensboro office to begin building your strategic architecture.
Partnering with a Strategic CPA: Cross-Border Solutions in Greensboro
Effective cross-border tax planning North Carolina is more than a seasonal obligation; it’s a year-round commitment to financial stewardship. Unlike traditional tax preparation that looks in the rearview mirror once a year, our proactive model focuses on continuous engagement. This approach ensures that every international transaction is structured with foresight, preventing the compliance gaps that lead to costly IRS inquiries. By maintaining a constant advisory relationship, we act as a vigilant guide, identifying opportunities for treaty benefits and tax mitigation long before the filing deadline arrives.
One of the most effective ways to maintain this level of control is by integrating monthly bookkeeping for small businesses into your global strategy. This real-time data flow allows us to monitor foreign account balances and asset thresholds as they fluctuate, ensuring that FBAR and FATCA reporting is accurate and timely. When your local accounting and international strategy are managed under one roof, you eliminate the fragmentation that often results in double taxation or missed credits.
If you’ve discovered past errors or unfiled foreign disclosure forms, it’s essential to address them through professional channels rather than waiting for an audit. We provide expert tax resolution in North Carolina, utilizing IRS disclosure programs to rectify historical non-compliance. This strategic defense is designed to protect your assets and reputation, providing a clear path back to full standing with federal authorities.
The ‘Strategic Architect’ Approach to International Tax
Our philosophy centers on being a “Strategic Architect” for your financial future. This means moving beyond reactive compliance to create a proactive framework for asset protection. We customize every plan to account for the unique nexus of North Carolina law and international tax treaties, particularly as the state’s corporate tax landscape evolves. This high level of professional representation doesn’t just minimize liability; it provides the calm confidence that your global interests are being managed with constant attention and intellectual rigor.
Next Steps for NC Residents and Business Owners
Securing your international position starts with a comprehensive review of your current standing. We recommend a mid-year strategic review to prepare for the 2026 tax year, allowing enough time to implement structural changes or resolve outstanding reporting issues. Whether you’re managing foreign rental properties or expanding a Piedmont Triad business into global markets, a consultative review of your international tax positions is the first step toward long-term stability.
- Identify any unfiled international returns and evaluate eligibility for IRS amnesty programs.
- Align your monthly financial reporting with international disclosure requirements.
- Establish a clear roadmap for future foreign investments or repatriating earnings.
We invite you to schedule a consultation at our Greensboro or High Point offices to begin building your cross-border tax planning North Carolina strategy. By partnering with a growth-oriented advisor, you ensure that your international success remains protected by a steady hand in a complex regulatory environment.
Securing Your Financial Future Across Borders
Navigating the intersection of local growth and international regulation requires more than just meeting annual deadlines; it demands a comprehensive architecture that anticipates global shifts. We’ve examined how FBAR and FATCA thresholds, paired with strategic treaty applications, form the pillars of a secure financial standing. For residents and business owners in the Piedmont Triad, the goal remains clear: minimize global tax liability while maintaining absolute IRS compliance through every stage of growth.
Mildrid Esua, CPA, PLLC provides the specialized FIRPTA withholding expertise and strategic IRS representation for tax resolution needed to protect your assets. With deep local roots in Greensboro and High Point, we serve as your vigilant guide through the complexities of cross-border tax planning North Carolina. Unlike traditional, reactive firms, we prioritize a proactive partnership that secures your interests year-round, ensuring that your international legacy is built on a foundation of stability and foresight.
Taking control of your international obligations today ensures long-term stability for your personal and professional interests. Secure your global interests with a strategic tax consultation and move forward with the calm confidence that your global trajectory is being managed with expert precision.
Frequently Asked Questions
What is the 10,000 dollar rule for foreign bank accounts?
The $10,000 rule refers to the aggregate filing threshold for the FBAR, or FinCEN Form 114. You must report your foreign financial accounts if their combined total value exceeds $10,000 at any point during the calendar year. This applies even if the balance only hit that mark for a single day. It’s a disclosure requirement, not a tax, but failing to report can lead to non-willful penalties starting at $16,536 in 2026.
Do I have to pay taxes in North Carolina on income earned abroad?
North Carolina residents are generally taxed on their worldwide income, regardless of where it was earned. Because the state uses federal Adjusted Gross Income as its starting point, any foreign income reported on your federal return flows through to your NC taxes. However, you can often mitigate this through federal credits or exclusions. Expert cross-border tax planning North Carolina ensures you don’t pay more than necessary to both the state and foreign jurisdictions.
How can I avoid the 15 percent FIRPTA withholding when selling my NC home?
You can reduce or eliminate the 15% FIRPTA withholding by applying for an IRS Withholding Certificate before your closing date. This certificate proves your actual tax liability is lower than the standard withholding amount. Additionally, if the sales price is $300,000 or less and the buyer intends to use the property as a primary residence, you may qualify for a full exemption. Early coordination with a Greensboro tax advisor is vital for these filings.
What happens if I forgot to file an FBAR in previous years?
If you’ve missed previous FBAR filings, the IRS offers several disclosure programs to help you catch up. The Streamlined Filing Compliance Procedures are often the best path for taxpayers whose failure to file was non-willful. This process allows you to report past accounts while significantly reducing or eliminating potential penalties. Waiting for the IRS to find the error is risky, as penalties for willful non-disclosure can exceed $165,353 or 50% of the account balance.
Is there a tax treaty between the US and my home country that affects my NC taxes?
While the U.S. maintains tax treaties with dozens of countries to prevent double taxation, these agreements are federal in nature. Because North Carolina’s tax system is tied to your federal return, treaty benefits that reduce your federal income will typically lower your NC taxable income as well. However, most treaties contain a “savings clause” that allows the U.S. to tax its citizens as if the treaty didn’t exist, which requires careful strategic navigation.
Can a local Greensboro CPA handle complex international tax filings?
Yes, a specialized local firm like Mildrid Esua, CPA, PLLC handles these complex requirements for residents in Greensboro, High Point, and Winston-Salem. Unlike larger national firms that may feel detached, we offer a proactive partnership that integrates your local business interests with global compliance needs. Our team handles everything from FIRPTA withholding to FBAR disclosures, ensuring your international assets are managed with vigilant stewardship and local expertise right here in the Piedmont Triad.
How does an S-Corp election affect my international tax obligations?
An S-Corp election can optimize self-employment tax for your domestic operations, but it brings strict rules for international interests. Only U.S. citizens or residents can be shareholders in an S-Corp, which complicates ownership for foreign nationals. Additionally, if your S-Corp owns foreign entities, you may face complex reporting requirements like GILTI. Proper cross-border tax planning North Carolina helps you weigh these benefits against the increased compliance burden of managing a global corporate structure.

Leave a Reply
Your email is safe with us.