What if the most powerful collection agency in the world decides your family’s front door is the key to settling your debt? It’s a terrifying thought that keeps homeowners awake at night, especially when certified letters arrive with frequency. If you’re feeling the weight of unpaid taxes, you’ve likely asked: can the IRS take my house in North Carolina? While the federal government possesses power, the reality is more nuanced than a simple ‘yes’ or ‘no.’ The process is complex, designed with legal safeguards that work in your favor when you have a vigilant guide by your side.
We understand the anxiety stemming from federal collection notices, but the IRS typically views home seizure as a last resort. This guide provides the clarity you need to move from uncertainty to informed decision-making. Unlike reactive strategies that only address problems after they peak, we’ll show you how to proactively navigate the 2026 collection landscape. You’ll discover the legal hurdles the IRS must clear, the 2026 North Carolina property exclusions that may offer relief, and a strategic roadmap to protect your primary residence through customized tax resolution.
Key Takeaways
- While the IRS possesses the legal authority to seize property, administrative hurdles and court approval requirements make the seizure of a primary residence an extremely rare event.
- You will learn the critical sequence of notices and the importance of the 30-day grace period to understand exactly when and how can the IRS take my house in North Carolina.
- Discover how North Carolina’s “Tenancy by the Entirety” laws and the IRS “Equity Rule” create significant barriers that often protect your home’s value from federal collection.
- We explore strategic settlement options like the Offer in Compromise and Partial Payment Installment Agreements that can resolve your tax debt without sacrificing your residence.
- Learn why shifting from a reactive stance to a proactive partnership with a tax resolution expert is the most effective way to secure your long-term financial stability.
Legal Reality: Can the IRS Actually Seize Your North Carolina Home?
The short answer is yes, but the reality is far more complex than a simple seizure. Under federal law, the IRS possesses the authority to seize and sell any type of real property to satisfy a tax debt. However, if you are asking, “can the IRS take my house in North Carolina,” you should know that the government views the seizure of a primary residence as an absolute last resort. Federal law requires the IRS to prove that no other reasonable alternative exists to collect the debt before they can move toward your front door.
This protection for your “Principal Residence” isn’t just a policy; it’s a legal hurdle that requires the IRS to obtain a court order from a U.S. District Court judge or magistrate. Unlike a bank account levy, which the IRS can execute with a simple notice, taking a home requires an immense amount of administrative effort and judicial oversight. To understand the Legal Reality of IRS Seizure, one must look at Internal Revenue Code section 6331, which outlines the rigorous standards the government must meet.
To better understand this concept, watch this helpful video:
The Power of the Federal Tax Lien vs. Physical Seizure
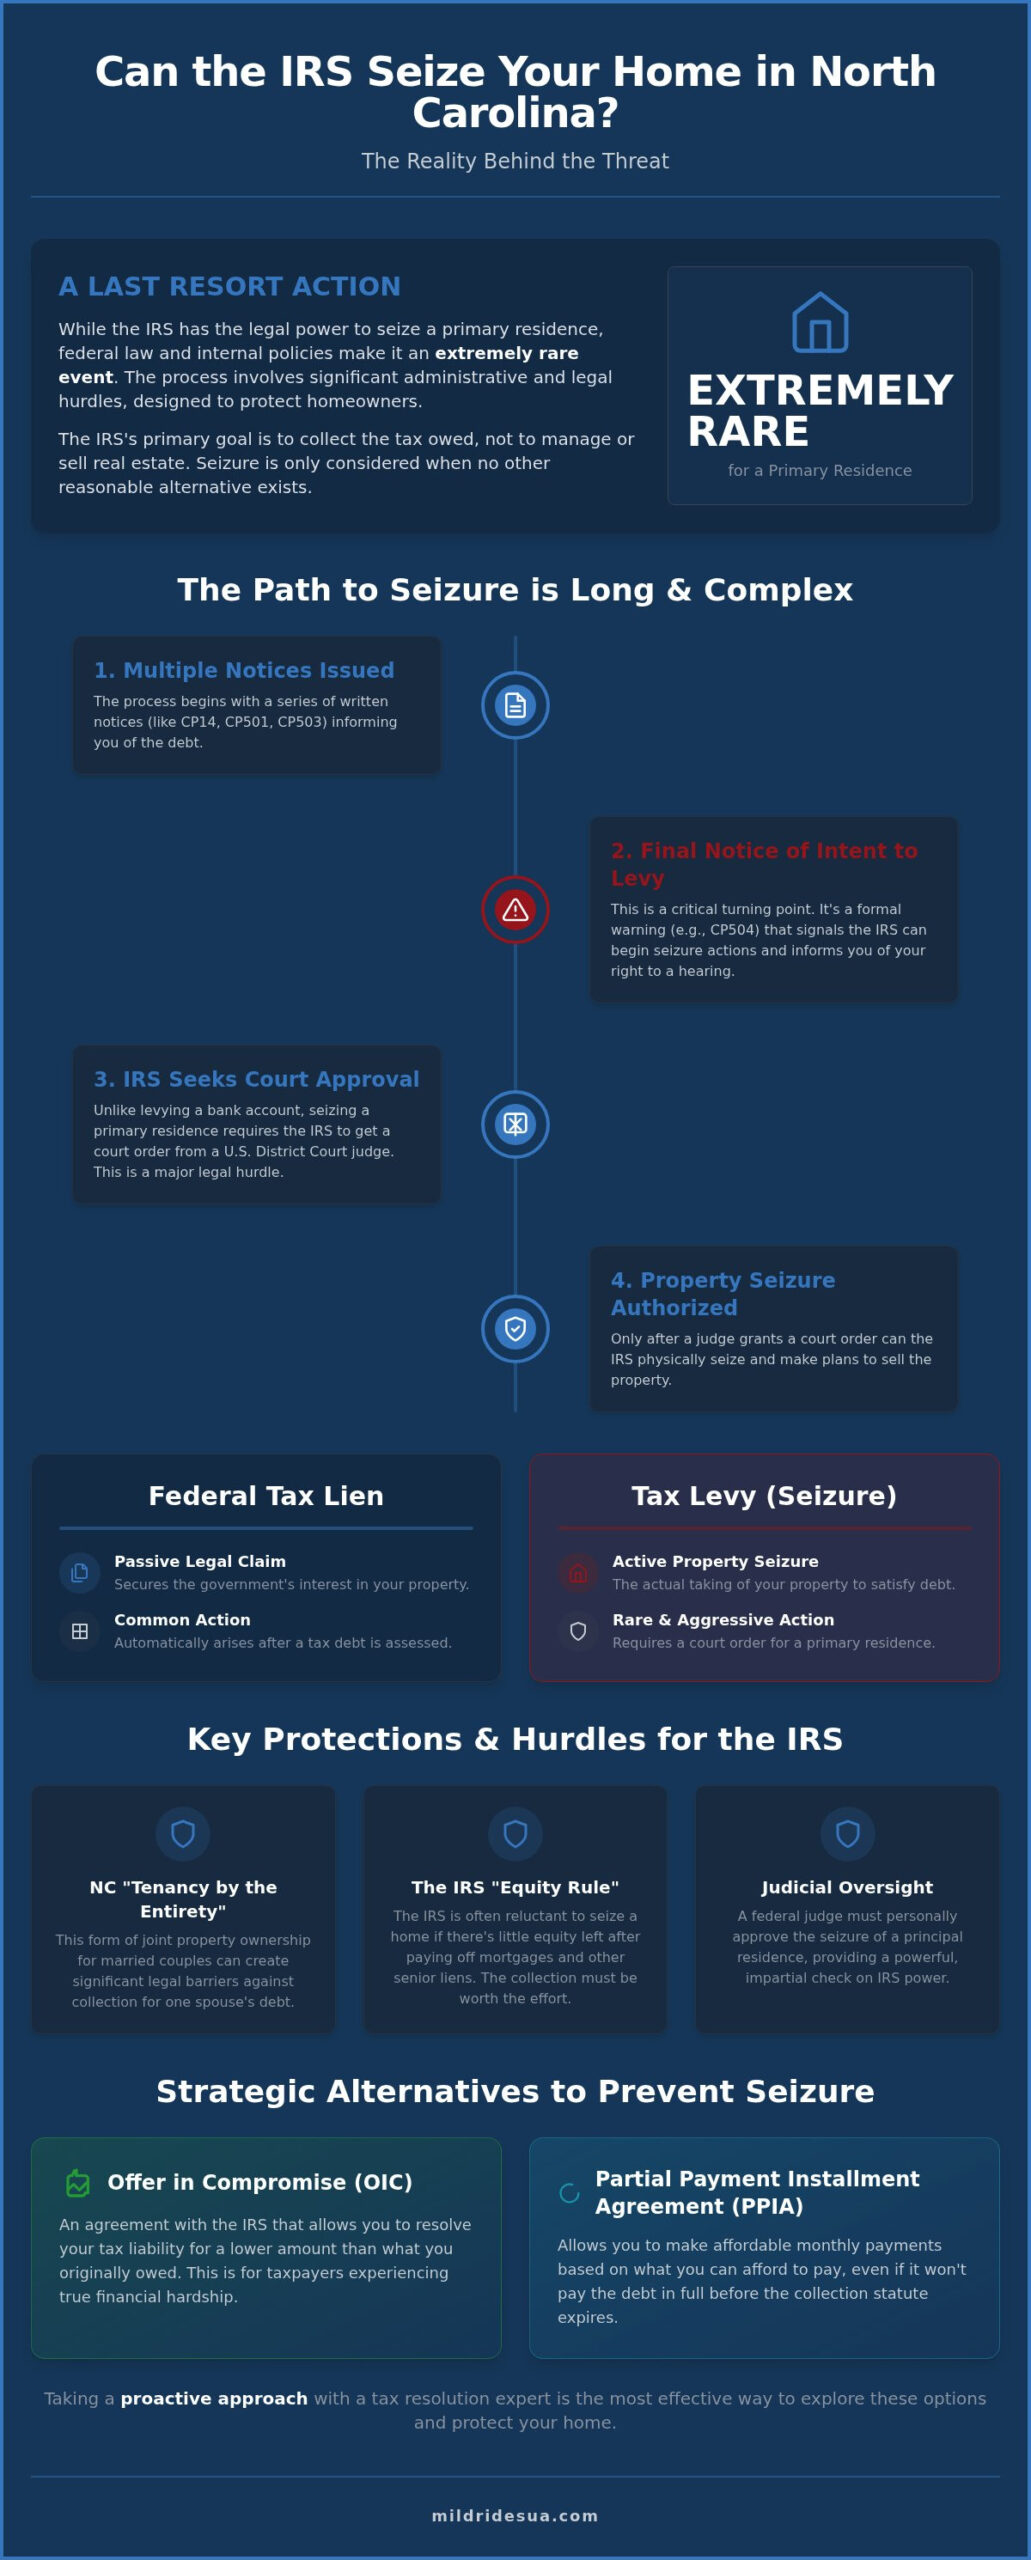
It’s vital to distinguish between a tax lien and a tax levy. A federal tax lien is a passive legal claim that attaches to your Greensboro or High Point property automatically once the IRS assesses a debt and sends notice. It acts as a public notice of debt that affects your credit and title, ensuring the government gets paid if you sell or refinance the home. A levy, however, is the active and aggressive physical seizure of the property. While a lien is common for those with back taxes, a levy on a primary residence is a rare, high-level enforcement action that only follows a long period of ignored notices.
North Carolina Homestead Exemptions and Federal Law
Many taxpayers mistakenly believe that North Carolina’s homestead exemptions will protect them from federal collection. In a typical civil lawsuit or state-level debt collection, NC law allows you to protect a portion of your home’s equity. However, the Supremacy Clause of the U.S. Constitution dictates that federal tax law overrides state exemptions. This means that while a local credit card company can’t touch your equity, the IRS technically can. Despite this power, the IRS often hesitates to override local property interests because the legal costs and public relations impact of displacing a family are significant. They’d much rather negotiate a strategic settlement than manage the fallout of a home sale.
Understanding that you still have leverage is the first step toward resolution. If you’re wondering can the IRS take my house in North Carolina, remember that their primary goal is payment, not property management. By acting as a strategic architect of your own defense, you can use these legal hurdles to force a more favorable settlement option.
The IRS Seizure Process: From Notice to Court Approval
The path to property seizure is paved with a methodical progression of paper. Before the government can even consider your primary residence, they must follow a rigid administrative sequence that offers multiple opportunities for intervention. This typically begins with the CP14 notice, followed by reminders like CP501 and CP503. The CP504 notice is the “urgent” warning that often precedes a levy on state tax refunds or bank accounts. However, when you ask, “can the IRS take my house in North Carolina,” you’re looking at a much more rigorous standard than these initial steps. For more details on these early stages, you can review The IRS Collection Process guide published by the agency.
Understanding the Final Notice of Intent to Levy
Receiving a Final Notice of Intent to Levy and Notice of Your Right to a Hearing is a critical turning point for Greensboro homeowners. This isn’t just another bill; it’s a 30-day countdown that demands immediate action. During this window, you have the legal right to request a Collection Due Process (CDP) hearing. By filing Form 12153, you effectively stop the clock on seizure actions while your case is reviewed. Unlike a reactive approach that waits for the hammer to fall, filing for a CDP hearing allows a strategic architect to present alternatives, such as an installment agreement or an Offer in Compromise, before the IRS can proceed further. This is the most effective way to answer the question of can the IRS take my house in North Carolina with a definitive “not today.”
The 26 U.S.C. § 6334(e)(1) Judicial Requirement
The IRS cannot simply show up and change the locks on your High Point home. Under 26 U.S.C. § 6334(e)(1), the government must obtain a written recommendation from an IRS District Director and a judicial order from a U.S. District Court judge. This involves a formal hearing where the taxpayer has the right to object and present a defense. The IRS carries a heavy burden of proof; they must demonstrate that the tax debt is valid, all administrative procedures were followed, and no other reasonable collection alternatives exist.
The judicial hearing is a significant barrier for the IRS. A judge won’t sign off on a seizure if the IRS hasn’t exhausted other options or if the seizure would create an “economic hardship” that leaves the taxpayer homeless. This is where professional advocacy becomes essential. We analyze your financial profile to prove that a seizure is not the most effective way to satisfy the debt. By the time the IRS seeks a court order, they must have already verified that the equity in the home is sufficient to pay off the debt and the costs of the sale. This high bar is why many homeowners find that proactive IRS representation provides the necessary leverage to resolve the debt before it ever reaches a courtroom.
Assessing the Risk: When is Your NC Home Actually Vulnerable?
The IRS isn’t in the business of property management; they are in the business of liquidating assets for cash. When you’re weighing the question, “can the IRS take my house in North Carolina,” the answer often depends on how much cash they’ll actually see at the end of the day. This is governed by the “Equity Rule,” a practical standard where the IRS declines to seize a home if the sale proceeds wouldn’t significantly reduce the tax debt after paying off senior claims. If the government can’t make a profit, they generally won’t move forward with a seizure.
North Carolina offers a unique protection known as “Tenancy by the Entirety.” For married couples who own a home together, this legal status means that if only one spouse owes the IRS, the government generally cannot seize the home to satisfy that individual’s debt. It’s a powerful shield that requires a sophisticated understanding of local property law to leverage correctly. Additionally, the IRS distinguishes between luxury homes and modest residences. A high-value estate with millions in equity is a much more attractive target than a modest family home in High Point where the mortgage nearly equals the value.
Primary Residence vs. Secondary or Rental Property
The risk profile shifts dramatically when moving from your main home to secondary assets. If you own a vacation rental in the Outer Banks or a mountain cabin near Asheville, these properties lack the “Principal Residence” protections found in the U.S. Code on IRS Levy and Seizure. Seizing a rental property doesn’t require the same high-level court order or a judge’s signature, making them low-hanging fruit for collection officers. The administrative burden of evicting a family from their main home is a legal hurdle the IRS prefers to avoid, whereas seizing a vacant or tenant-occupied investment property is relatively straightforward.
The Equity Factor: Is it Worth it for the IRS?
The IRS uses a specific formula to decide if a seizure is worth the effort. They start with a “forced sale value,” which is typically 80% of the fair market value. From that number, they subtract several key figures:
- The remaining balance of your existing mortgage.
- Unpaid North Carolina property taxes.
- Estimated selling costs and administrative fees.
If the remaining amount is negligible, the IRS will likely walk away. They aren’t interested in a no-equity seizure because it doesn’t serve their goal of debt collection. Navigating these calculations requires an Expert Tax Resolution in North Carolina approach, where we act as strategic architects to prove to the IRS that your home is not a viable source of collection. By demonstrating a lack of net equity, we can often remove the threat of seizure before it ever escalates. Knowing can the IRS take my house in North Carolina is only half the battle; knowing why they might choose not to is where your defense begins.
Strategic Alternatives to Prevent IRS Property Seizure
The IRS is fundamentally a financial institution, not a real estate agency. They don’t want the burden of managing or selling your home; they want a predictable path to debt satisfaction. When you’re asking, “can the IRS take my house in North Carolina,” the answer is often found in the strategic alternatives you propose before the situation reaches a boiling point. Unlike a reactive defense that only responds to threats, a proactive strategy focuses on providing the government with a more attractive financial outcome than a forced sale.
The Offer in Compromise (OIC) as a Shield
An Offer in Compromise (OIC) acts as a powerful legal shield for your primary residence. Once we submit a viable OIC, the IRS typically pauses most collection activities while they evaluate the proposal. We act as a Strategic Architect to calculate your Reasonable Collection Potential (RCP), which is the total amount the IRS can realistically expect to collect from your assets and future income. By presenting a well-structured OIC, we demonstrate that a cash settlement is more efficient for the government than the high administrative costs and logistical headaches of a public auction. The IRS prefers a certain settlement over the uncertainty of a property sale.
Hardship Status and Collection Due Process
For taxpayers facing significant financial strain, proving “Currently Not Collectible” (CNC) status can provide immediate relief. Hardship Status serves as a temporary freeze on IRS collection actions, providing vital breathing room while we negotiate a permanent resolution. We use Form 433-A to provide a detailed financial snapshot, proving that seizing your home would prevent you from meeting basic living expenses.
During a Collection Due Process (CDP) hearing, we don’t just ask for leniency; we propose specific alternatives to seizure. This might include a Partial Payment Installment Agreement (PPIA), which allows you to pay what you can afford over time while keeping your assets intact. We may also explore refinancing your Greensboro home or securing an equity loan to settle the debt in a lump sum. The goal is to maintain your stability while satisfying the government’s demand for payment.
For small business owners, managing future liabilities is just as critical as resolving past debt. Implementing an S Corp Election for Self-Employment Tax can significantly reduce your ongoing tax burden, ensuring you don’t fall back into the collection cycle. If you’re ready to move from anxiety to a strategic plan, our tax resolution services provide the vigilant stewardship required to protect your home and your financial future.
Proactive IRS Representation: Why Expert Help is Essential in Greensboro
Many homeowners wait until a Final Notice arrives before they begin to consider their defense. This reactive posture creates unnecessary risk and limits the strategic options available for resolution. Unlike a traditional legal defense that focuses solely on the litigation aspect of tax debt, our approach as a Strategic Architect involves building a comprehensive financial fortress. We focus on long-term stability, ensuring that your primary residence remains a secure asset rather than a point of vulnerability. By integrating tax resolution into a broader 2026 Strategic Tax Planning Guide, we move beyond mere crisis management into a philosophy of vigilant stewardship.
The Role of a CPA in Tax Resolution
Accurate bookkeeping serves as your primary line of defense against an IRS levy. When the government questions your “Reasonable Collection Potential,” having pristine financial records allows us to negotiate from a position of absolute clarity and strength. A CPA doesn’t just fill out forms; we use financial data to tell a compelling story of your economic reality. This intellectual depth is what often stops a seizure in its tracks. As your Vigilant Guide, we manage the complex, high-stakes interactions with the IRS so you don’t have to face the federal government alone. This proactive partnership ensures that every financial decision you make today is designed to safeguard your interests tomorrow.
Navigating the NC Tax Landscape
Greensboro and High Point entrepreneurs often face the dual pressure of federal collection and local tax liens. Unfiled returns are a particularly solvable problem, yet they remain one of the most common triggers for aggressive IRS action. If you’re still asking, “can the IRS take my house in North Carolina,” it’s likely because these unfiled years have created a vacuum of information that the IRS fills with their own, often less favorable, assessments. We specialize in resolving these complexities by aligning your state and federal compliance strategies into one cohesive plan.
Our commitment is to act as a growth partner, providing the steady hand you need in a complex regulatory environment. We help you navigate the transition from financial complexity to informed, confident decision-making. If you are ready to secure your home and your future with a dedicated advisor, schedule a consultation with Mildrid Esua, CPA today. By taking action now, you can transform a moment of anxiety into a long-term strategy for stability and peace of mind.
Securing Your Primary Residence Through Strategic Planning
The weight of a federal tax debt can feel overwhelming, but clarity is the ultimate antidote to anxiety. While the technical answer to can the IRS take my house in North Carolina is yes, the administrative and legal hurdles involved make it a rare event for those who take proactive steps. By understanding the judicial requirements and the “Equity Rule,” you’ve already shifted from a position of fear to one of informed strategy. This knowledge is your first line of defense in protecting your family’s stability.
Unlike a reactive approach that waits for the next notice, a partnership with a Strategic Architect allows you to resolve unfiled returns and liens before they escalate. We provide expert IRS representation in Greensboro and strategic tax resolution for small businesses, ensuring a vigilant stewardship of your financial interests. Your home is more than just a physical asset; it’s the foundation of your future. We’re here to help you navigate the transition from complexity to a clear, manageable roadmap that prioritizes your long-term security.
Secure Your Home and Resolve Your Tax Debt with Mildrid Esua, CPA today. You don’t have to face the federal government alone when you have a steady hand to guide you toward peace of mind and financial recovery.
Frequently Asked Questions
Can the IRS take my house if my spouse owes taxes but I do not?
In North Carolina, the legal concept of “Tenancy by the Entirety” usually prevents the IRS from seizing a primary residence if only one spouse owes the debt. If you own the home together and the tax liability belongs solely to your partner, the government cannot force a sale to satisfy that individual debt. This protection is a cornerstone of NC property law. If you filed jointly or both have liabilities, this shield no longer applies.
How long does the IRS have to seize my house in North Carolina?
The IRS generally has a 10-year statute of limitations to collect unpaid taxes from the date of assessment. While they can pursue seizure at any point during this decade, the physical act of taking a home requires months of administrative notices and judicial approvals. If you are wondering can the IRS take my house in North Carolina after several years of silence, remember that they can refile liens to extend their reach until the debt expires.
What happens if the IRS seizes my house but it doesn’t sell for enough to pay the debt?
If a seized home sells for less than the total tax liability, you remain responsible for the remaining balance. The IRS applies the net proceeds from the sale, after paying off the mortgage and selling costs, to your tax account. Because the IRS sells properties at a “forced sale value,” which is often lower than fair market value, you could lose your home and still carry a heavy financial burden. This is why proactive settlement is essential.
Can I stop an IRS house seizure by filing for bankruptcy in NC?
Filing for bankruptcy in North Carolina triggers an “automatic stay,” which immediately halts most IRS collection actions, including the seizure of your home. While bankruptcy provides a temporary reprieve, it doesn’t always eliminate the underlying tax debt. Some older income tax debts might be dischargeable, but newer liabilities and tax liens often survive the bankruptcy process. It’s a powerful tool to stop a sale, but it requires a long-term resolution strategy to be effective.
Does the IRS have to provide notice before showing up at my door?
The IRS cannot legally seize your home without providing multiple written warnings. You must receive a Final Notice of Intent to Levy and a Notice of Your Right to a Hearing at least 30 days before any seizure occurs. Taking a primary residence in Greensboro requires a specific court order signed by a federal judge. The IRS won’t simply appear at your door to change the locks without a lengthy, documented legal process and verified judicial approval.
Can the IRS take my retirement account and my house at the same time?
The IRS possesses the authority to levy both retirement accounts and real estate simultaneously to satisfy a large debt. However, they typically prioritize liquid assets like bank accounts or wages because these are easier to process. Seizing a home is an administrative nightmare that requires judicial oversight. While they can technically target both, they prefer to exhaust easier collection methods before moving toward the complex process of displacing a family from their primary residence.
Will the IRS take my house if I am currently on a payment plan?
No, the IRS will not seize your house if you are in compliance with an approved installment agreement. An active payment plan protects your assets from levy and seizure actions. This is why establishing a formal agreement is a primary goal for those asking can the IRS take my house in North Carolina. As long as you make your payments on time and stay current with future tax filings, your primary residence remains secure under federal collection standards.
What should I do if I receive a Notice of Seizure (Form 2433)?
Receiving Form 2433 is a critical emergency that signals the IRS has already taken legal possession of your property. You typically have a brief 10-day window to stop the public notice of sale. At this stage, you must act immediately to file for a stay or negotiate a last-minute resolution. This level of crisis requires a vigilant guide to navigate the U.S. District Court requirements and protect your remaining property equity before the hammer falls.