

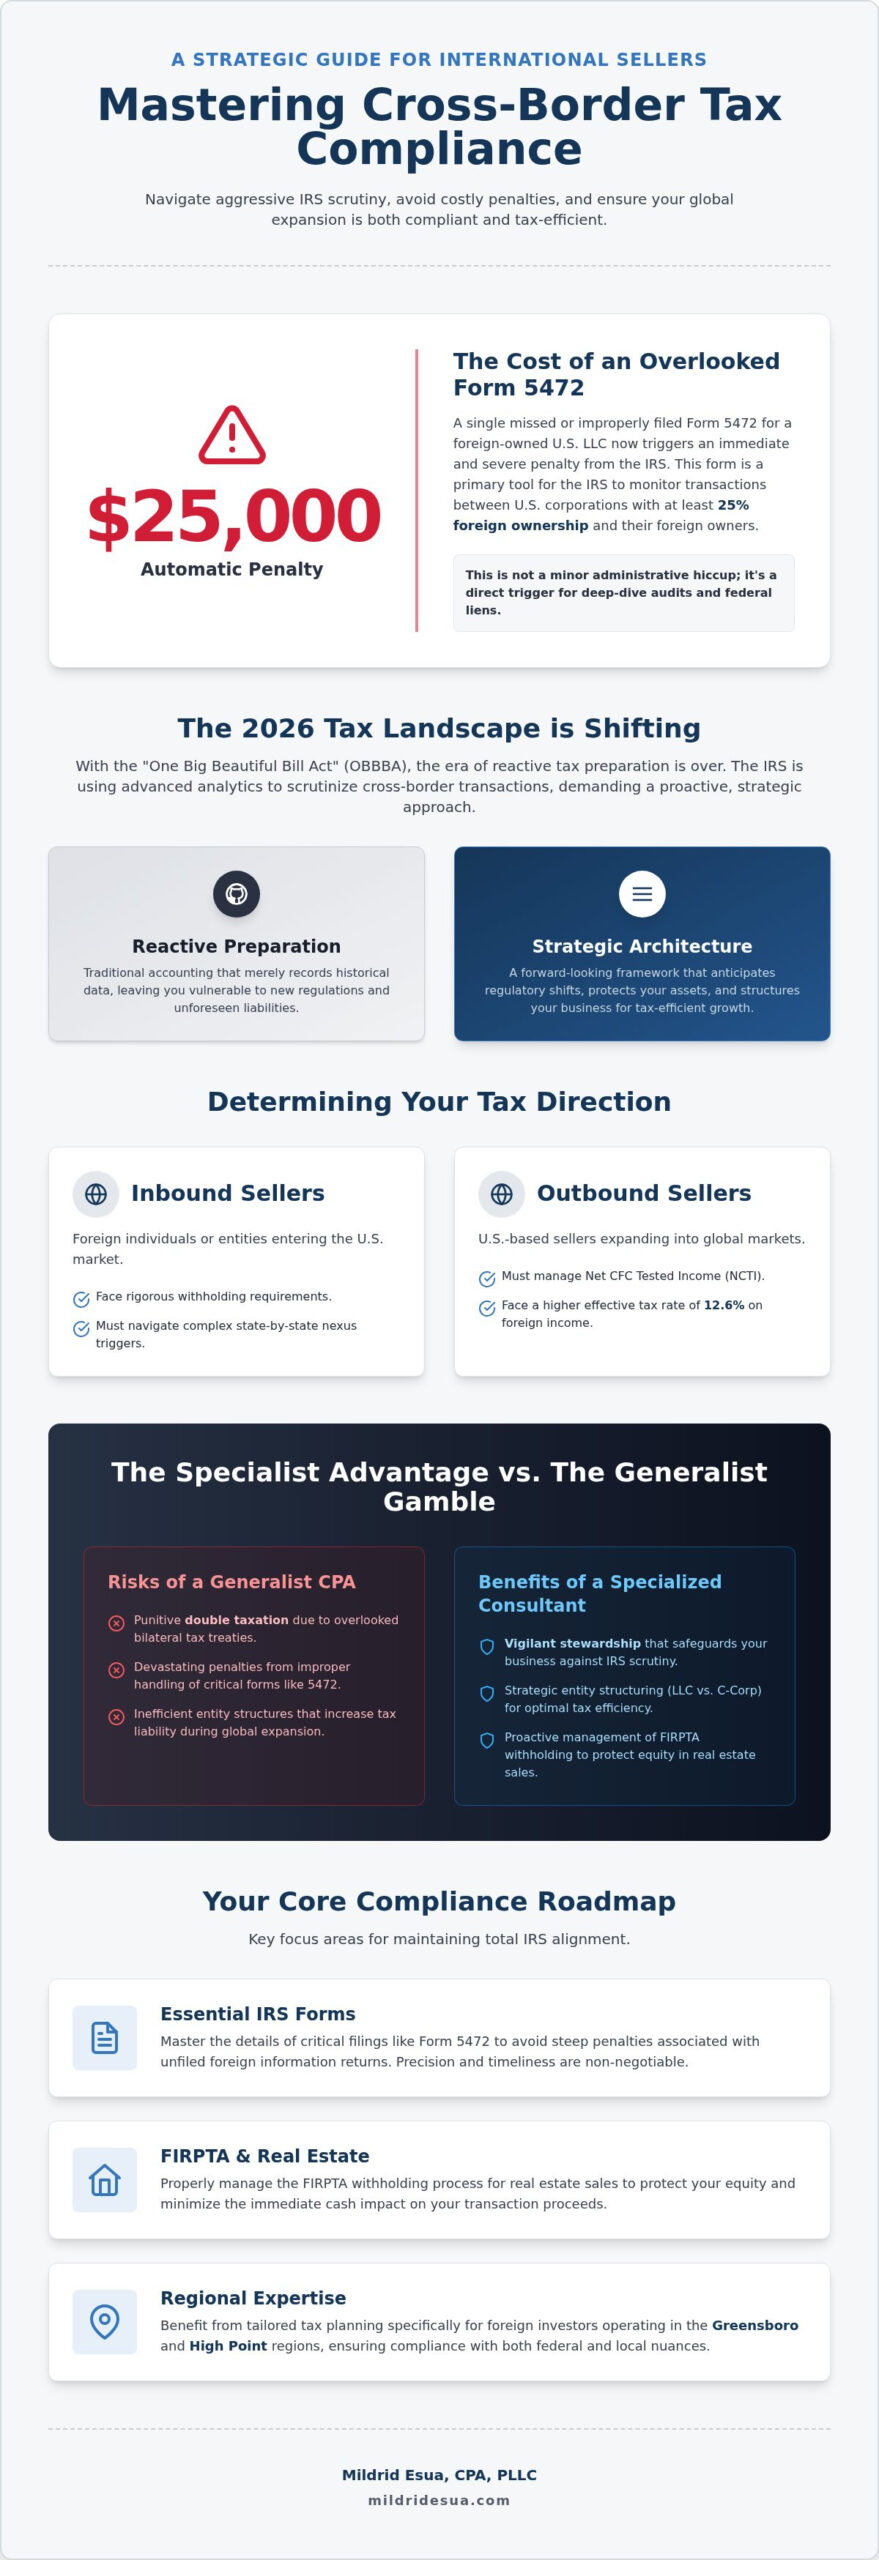
Did you know that a single overlooked Form 5472 for a foreign-owned U.S. LLC now triggers an automatic $25,000 penalty? For many entrepreneurs, the dream of global expansion is often clouded by the fear of aggressive IRS intervention and the heavy burden of double taxation. You deserve to focus on your growth without the constant anxiety that a missed filing or a misunderstood FIRPTA withholding rate will erode your hard-earned profits. It’s a heavy weight to carry, especially as the 2026 tax landscape introduces complex shifts through the One Big Beautiful Bill Act. Partnering with a specialized tax consultant for international sellers transforms this complexity into a structured roadmap for long-term stability.
By choosing a proactive advisor, you gain more than just a preparer; you secure a vigilant guide to oversee your global interests. This article provides a clear roadmap to mastering cross-border compliance, ensuring you minimize liabilities while maintaining total IRS alignment. We’ll examine the strategic architecture needed to navigate the new NCTI rates, manage property sale withholdings, and protect your investments in Greensboro, High Point, and the surrounding areas. You’ll discover how a deliberate partnership can replace confusion with calm, strategic confidence.
Key Takeaways
- Discover how a tax consultant for international sellers serves as a strategic architect to safeguard your business against aggressive IRS scrutiny and costly filing errors.
- Learn to identify and manage essential IRS forms, such as Form 5472, to avoid the steep penalties associated with unfiled foreign information returns.
- Gain clarity on selecting the optimal entity structure, whether it’s an LLC or C-Corp, to ensure your global expansion remains both compliant and tax-efficient.
- Master the FIRPTA withholding process for real estate sales to protect your equity and minimize the immediate impact on your transaction proceeds.
- Explore the benefits of proactive IRS representation and tailored tax planning designed specifically for foreign investors operating in the Greensboro and High Point regions.
The 2026 International Tax Landscape: Why Sellers Need a Specialized Consultant
The 2026 tax year marks a definitive shift in how the IRS monitors global commerce. With the full implementation of the One Big Beautiful Bill Act (OBBBA), the era of reactive tax preparation has ended. Unlike traditional accountants who merely record historical data, a specialized tax consultant for international sellers acts as a strategic architect. This role involves building a protective framework that anticipates regulatory shifts before they impact your liquidity. The IRS has significantly intensified its focus on foreign-owned U.S. entities, deploying advanced data analytics to flag cross-border transactions that appear inconsistent with new 2026 reporting standards. This isn’t just about filing forms; it’s about vigilant stewardship in an environment where the cost of a single error has never been higher.
Inbound vs. Outbound: Determining Your Tax Direction
Establishing a compliant footprint begins with identifying your primary tax direction. Inbound sellers, which include foreign individuals or entities entering the U.S. market, face rigorous withholding requirements and nexus triggers that vary significantly by state. Conversely, outbound U.S. sellers must now navigate the complexities of Net CFC Tested Income (NCTI), which has replaced the previous GILTI regime with a higher effective tax rate of 12.6%. Both paths require a sophisticated grasp of international taxation principles to effectively manage the tension between territorial and residence-based systems. IRS scrutiny is currently at an all-time high for digital goods and global services, where the “source” of income is often a point of contention.
The Risks of Generic Accounting in a Global Economy
Entrusting global operations to a generalist CPA is a high-stakes gamble. Generalists frequently overlook the subtle nuances of bilateral tax treaties, which often results in the punitive reality of double taxation. A recurring and devastating mistake involves the improper handling of Form 5472 for foreign-owned U.S. LLCs. In 2026, the penalty for failing to file this form correctly starts at a staggering $25,000 per violation. These aren’t just administrative hiccups; they’re triggers for deep-dive audits and federal liens. When these systemic errors occur, businesses often find themselves in desperate need of expert tax resolution North Carolina to resolve unfiled returns and mitigate financial damage. Professional tax planning ensures your international interests remain a source of growth rather than a liability.
Core Compliance: Essential IRS Forms for International Sellers
Maintaining global financial transparency is no longer an optional exercise in record-keeping; it’s a foundational requirement for business survival. For the 2026 tax year, the IRS has tightened its grip on how foreign interests are disclosed. This shift demands a “Strategic Architect” approach to ensure every cross-border transaction is documented with precision. A qualified tax consultant for international sellers doesn’t just react to deadlines. They build a year-round compliance framework that protects your equity from aggressive enforcement actions. Failure to disclose foreign assets or related-party transactions can lead to catastrophic financial consequences that far outweigh the cost of proactive stewardship.
Form 5472 and the 25% Foreign Ownership Rule
Form 5472 serves as the IRS’s primary window into the operations of U.S. corporations with at least 25% foreign ownership. This includes foreign-owned single-member LLCs, which are often treated as “disregarded entities” but still carry heavy reporting burdens. The focus here is on “reportable transactions,” such as loans, sales, or rents between the U.S. entity and its foreign owners. In 2026, the penalty for failing to file a timely or accurate Form 5472 remains a staggering $25,000. Unlike simple income reporting, this form requires a deep dive into your corporate structure. Engaging a specialized tax advisor ensures your documentation meets these rigorous standards long before the filing deadline.
FBAR and FATCA: Navigating Foreign Account Reporting
Transparency extends beyond the business entity to the individuals behind it. U.S. sellers with global interests must navigate the dual requirements of FBAR (FinCEN Form 114) and FATCA (Form 8938). While they overlap, they serve different masters. FBAR is required if the aggregate value of your foreign financial accounts exceeds $10,000 at any point during the year. FATCA reporting, filed with your tax return, typically kicks in at a $50,000 threshold for individuals living in the U.S., though these limits fluctuate based on your residency status. If you’ve missed previous filings, proactive disclosure through specialized tax resolution is the only way to mitigate potential 40% penalties on the highest balance of those accounts.
The 2026 calendar is unforgiving. March 16, 2026, is the hard deadline for S-Corporations and Partnerships to file their returns. By April 15, 2026, C-Corporations, individuals filing 1040-NR, and foreign-owned disregarded entities must have their documentation finalized. A tax consultant for international sellers provides the steady hand needed to meet these dates with total confidence, transforming a season of risk into a period of strategic stability.
Strategic Entity Structuring for Global Market Expansion
Building a business on a global scale requires more than just market research; it demands a structural foundation that can withstand international scrutiny. Unlike enterprise-level firms that offer abstract planning, a specialized tax consultant for international sellers provides a tailored blueprint for owner-operators and small-to-medium enterprises. The decision to operate as a U.S. Branch, a limited liability company (LLC), or a C-Corporation shouldn’t be made in a vacuum. Each path carries distinct implications for how your global profits are recognized and taxed under the 2026 rules. For instance, the flat 21% federal corporate tax rate makes the C-Corp a stable choice for many, especially when leveraging the 14% effective rate on Foreign-Derived Deduction Eligible Income (FDDEI). However, this must be balanced against the risk of double taxation on distributions to foreign owners.
For U.S.-based entrepreneurs expanding outward, an S Corp election for self employment tax optimization can drastically improve your bottom line. By structuring your compensation into a reasonable salary and business distributions, you protect your growth capital from excessive payroll taxes. Your ability to claim foreign tax credits also hinges on this initial selection. Pass-through entities allow these credits to flow directly to your personal return, whereas corporate structures may require more complex calculations to avoid losing the value of taxes paid abroad. A vigilant guide ensures these credits are maximized, preventing the erosion of your global profits.
US LLC vs. C-Corp for Foreign Sellers
Foreign sellers often gravitate toward the “pass-through” simplicity of an LLC, yet this structure requires careful management of Effectively Connected Income (ECI). If your U.S. activities are deemed a trade or business, your income is taxed at graduated individual rates, which can exceed the corporate flat rate. Seeking professional business entity selection tax advice is the only way to ensure your structure aligns with your long-term exit strategy. This proactive approach prevents the IRS from reclassifying your income or disputing your deductions years down the line, providing the stability needed for sustained expansion.
Permanent Establishment and Nexus in E-commerce
In the digital age, your physical location is only one part of the tax equation. The concept of Permanent Establishment (PE) remains a cornerstone of international treaties, but states like North Carolina have expanded their reach through economic nexus. If your sales in Greensboro or High Point cross specific revenue or transaction thresholds, you’ve triggered a tax obligation regardless of where you’re based. E-commerce sellers should monitor this checklist to assess their footprint:
- Third-party fulfillment centers (like Amazon FBA) creating physical nexus through inventory storage.
- Economic thresholds, typically $100,000 in sales or 200 transactions, in individual states.
- The presence of remote employees, sales agents, or independent contractors in North Carolina.
Staying ahead of these triggers ensures you aren’t blindsided by retroactive state assessments that can cripple your margins.
FIRPTA and Real Estate: Critical Guidance for Foreign Sellers
Selling U.S. real estate as a foreign person involves a complex layer of federal oversight known as the Foreign Investment in Real Property Tax Act (FIRPTA). While many generalist firms offer only a surface-level overview, a dedicated tax consultant for international sellers understands that the 15% withholding on the gross sales price is often a significant hurdle to a successful closing. In 2026, this 15% rate remains the standard for most transactions, though specific exceptions can provide relief. For instance, if the sales price is between $300,001 and $1,000,000 and the buyer intends to use the property as a primary residence, the withholding rate may be reduced to 10%. For transactions of $300,000 or less with a similar buyer intent, the withholding can be eliminated entirely. These nuances require a proactive approach to prevent unnecessary capital from being tied up by the IRS.
Obtaining a FIRPTA Withholding Certificate
The most effective way to protect your transaction proceeds is through the timely filing of Form 8288-B. This application for a withholding certificate allows the IRS to verify that your actual tax liability is substantially less than the standard 15% withholding. To be valid, this form must be submitted to the IRS on or before the day of the property transfer. When a certificate request is pending, the buyer can place the disputed funds in an interest-bearing escrow account rather than remitting them immediately to the government. This process requires a vigilant guide who can coordinate with closing attorneys and title companies to ensure every document is processed with precision, maintaining your liquidity during the transition.
Capital Gains and the Foreign Seller
It’s vital to remember that FIRPTA is a withholding mechanism, not a final tax assessment. Your actual liability is calculated on the net capital gain, which requires a meticulous record of the property’s adjusted basis. This is where monthly bookkeeping for small businesses becomes indispensable. Without documented proof of capital improvements, legal fees, or acquisition costs, you risk overpaying the IRS. For investors looking to maintain their U.S. footprint, a 1031 exchange offers a strategic path to defer taxes by reinvesting proceeds into a “like-kind” property. This allows for the continued growth of your portfolio without the immediate erosion caused by capital gains taxes.
Navigating a 2026 real estate closing requires a clear, synchronized timeline. From the initial contract negotiation to the final filing of the 1040-NR, every step must be managed to prevent costly delays or IRS intervention. If you’re preparing for a sale in Greensboro or the surrounding North Carolina areas, securing a FIRPTA withholding accountant early in the process is the most effective way to ensure your equity is preserved and your compliance is total.
The Proactive Advantage: Partnering with a Greensboro International Tax Expert
Choosing a tax consultant for international sellers involves more than finding someone to fill out forms; it’s about securing a Strategic Architect who understands the nuances of the North Carolina business environment. Unlike massive, impersonal global firms that offer detached service from a distant office, Mildrid Esua, CPA, PLLC provides a deeply engaged partnership for businesses in Greensboro and High Point. We don’t just look backward at your previous year’s performance. Instead, we focus on the long-term trajectory of your global operations, ensuring that local state tax obligations in Winston-Salem or Kernersville don’t conflict with your federal international requirements. This year-round advisory relationship replaces the stress of seasonal tax preparation with a steady, methodical rhythm of compliance and growth.
IRS Representation and Resolution for International Sellers
When the IRS flags an unfiled foreign information return or a discrepancy in FIRPTA withholding, the stakes are high. Our firm adopts the philosophy of a Vigilant Guide, representing your interests with strategic intent before federal authorities. We specialize in resolving complex issues such as back taxes and unfiled Form 5472 or 5471 returns, which often carry those $25,000 penalties mentioned earlier. A proactive defense is always more effective than a reactive scramble. By prioritizing professional tax preparation Greensboro, you create a robust compliance shield that minimizes the likelihood of an audit while positioning your business for sustainable expansion.
Integrating Bookkeeping with International Tax Strategy
Precision in international tax requires a foundation of immaculate financial data. By integrating small business accountant Charlotte strategies into your bookkeeping, we help you track global income streams with absolute clarity. Cloud-based accounting tools allow us to maintain real-time oversight of your transactions, ensuring that your tax footprint is managed as it grows, not months after the fact. This continuous engagement ensures that your business remains agile, allowing you to make informed decisions based on accurate data rather than guesswork.
The complexities of 2026 global compliance demand a partner who stays continuously engaged with your financial health. Whether you’re navigating the OBBBA changes or managing real estate equity, a specialized tax consultant for international sellers provides the professional authority needed to protect your interests. Don’t leave your global expansion to chance. Contact Mildrid Esua, CPA, PLLC today to schedule a comprehensive international tax consultation and secure the vigilant stewardship your business deserves.
Securing Your Global Legacy Through Strategic Stewardship
Global expansion represents a significant milestone for any entrepreneur, yet it requires a structural foundation that prioritizes long-term stability over seasonal convenience. As we move through the complexities of the 2026 tax landscape, the difference between growth and liability often rests on the quality of your advisory partnership. Choosing a specialized tax consultant for international sellers ensures that your cross-border interests are managed with constant attention and strategic depth. By mastering entity selection and the nuances of FIRPTA, you protect your equity from unnecessary IRS intervention.
Mildrid Esua, CPA, PLLC stands as your vigilant guide, offering expert FIRPTA withholding assistance and dedicated IRS representation in Greensboro. Our specialized international small business accounting provides the clarity you need to navigate global markets with calm confidence. Unlike firms that offer only reactive services, we act as your growth partner to ensure your complex interests remain secure. It’s time to replace the anxiety of compliance with a roadmap for success.
Schedule Your Strategic International Tax Consultation with Mildrid Esua, CPA to secure your financial future. Your journey toward global mastery starts with a single, informed decision.
Frequently Asked Questions
Do international sellers have to pay US income tax?
Yes, international sellers are generally liable for U.S. tax if their earnings are “Effectively Connected Income” (ECI) with a U.S. trade or business or qualify as “Fixed, Determinable, Annual, or Periodical” (FDAP) income. You must navigate these classifications to determine if you owe tax at graduated rates or a flat 30% withholding. A tax consultant for international sellers helps identify applicable treaties that might reduce these liabilities, ensuring your global revenue isn’t unfairly taxed twice.
What is the penalty for not filing Form 5472?
The initial penalty for failing to file a timely or accurate Form 5472 in 2026 is a significant $25,000. This applies to foreign-owned U.S. corporations or disregarded entities, such as single-member LLCs, that fail to report required transactions with related parties. If the failure continues after IRS notification, additional penalties of $25,000 are assessed every 30 days. Vigilant stewardship is required to maintain the detailed records necessary to avoid these aggressive enforcement actions.
Can a foreign seller avoid the 15% FIRPTA withholding?
Foreign sellers can often reduce or eliminate the 15% withholding by obtaining a Withholding Certificate from the IRS before the transaction closes. This certificate confirms that the actual tax due on the capital gain is less than the standard withholding amount. Additionally, transactions under $300,000 where the buyer uses the property as a primary residence may be exempt. Strategic planning with a FIRPTA expert ensures your equity remains accessible rather than tied up in IRS escrow.
How does a tax treaty affect my US tax obligations as a seller?
Tax treaties are critical tools that can lower or eliminate U.S. withholding taxes on passive income like royalties or interest. They also define the “Permanent Establishment” threshold, which determines whether your business activities trigger U.S. income tax obligations in the first place. Without a treaty, you might face a flat 30% tax on certain income types. Our firm acts as a strategic architect, applying these bilateral agreements to protect your international profit margins and prevent double taxation.
What is the difference between ECI and FDAP income for international sellers?
Effectively Connected Income (ECI) refers to earnings from a U.S. trade or business, taxed at graduated rates after allowable deductions. Fixed, Determinable, Annual, or Periodical (FDAP) income is typically passive, such as dividends or rent, and is taxed at a flat 30% on gross amounts unless a treaty applies. Distinguishing between the two is vital for accurate tax preparation. A tax consultant for international sellers ensures your income is categorized correctly to minimize your overall federal liability.
Do I need a US-based CPA if I am selling from another country?
Maintaining a U.S.-based CPA is essential for navigating the complex web of federal and state regulations, especially in North Carolina. A local expert provides the vigilant guide philosophy required for IRS representation and ensures you meet state-specific nexus requirements in cities like Greensboro and Winston-Salem. Unlike overseas firms, a U.S. CPA understands the latest 2026 IRS procedural shifts and can act as your authorized representative during audits or tax resolution processes.
How do I report foreign bank accounts to the IRS?
Foreign accounts are reported through two primary mechanisms: the FBAR (FinCEN Form 114) and FATCA (Form 8938). The FBAR is required if the aggregate value of all foreign accounts exceeds $10,000 at any time during the calendar year. FATCA applies to individuals with higher thresholds of foreign assets and is filed with your annual return. Accurate reporting is non-negotiable, as penalties for non-willful violations are steep. We integrate this reporting into your comprehensive strategy to ensure total financial transparency.
What is the deadline for international business tax filings in 2026?
For the 2026 tax year, the deadline for S-Corporations and Partnerships is March 16, 2026. C-Corporations, sole proprietorships, and foreign-owned disregarded entities must file by April 15, 2026. Meeting these dates is critical to avoid the high-cost penalties associated with late international disclosures. Our team provides the methodical, steady oversight needed to ensure all global reporting is finalized well before these unforgiving IRS cutoffs, protecting your business from unnecessary financial strain in Burlington or High Point.

Leave a Reply
Your email is safe with us.